💬 Consult Now
October 5, 2026

How Family Offices in India Can Plan Global Mobility for the Next Generation

Most family offices in India have strong advisors for investments, tax and compliance. Yet one of the most important questions is often ignored until it becomes urgent: what is the plan for the children?

In family after family, we now see the 3rd and 4th generation wanting to take their school and university education out of India. Many of them also wish to obtain residency of another country. These questions are rarely discussed when the children are young, which is exactly when planning is most powerful. By the time the family sits down to think about it, the child is 16 or 17, the applications are due, and decisions are made in a hurry.

Global mobility is not running away from the family business

In many families, the idea of a child studying abroad or holding foreign residency raises an unspoken worry: will the next generation drift away from the family business?

We encourage families to see it differently. Global mobility, planned well, is not a family member leaving the business. It is a strategy to expand it. A next-generation member with international education, global networks and residency or citizenship options can:

  1. Open new markets and build overseas partnerships for the family business.
  2. Help create a global investment portfolio and new asset classes beyond India.
  3. Support tax planning across jurisdictions, within the law.
  4. Give the family access to better banking, insurance, healthcare and lifestyle options.
  5. Protect the family with a second home base if circumstances change.

Many of the most successful business families in the world have used this approach. They send the next generation out to learn, build and connect, and bring that value back into the family enterprise.

The gap we see most often

Education, residency, citizenship, cross-border wealth and succession are usually handled by different people, or not handled at all. The result is a familiar pattern.

A child turns 15 or 16 and the family starts thinking about studying abroad. The country is chosen first, often based on rankings, peer influence or what a relative’s child did. The program comes second. Nobody asks where this child is likely to live and work at 30, what visa pathway the course leads to, or how the funding should be structured under Indian foreign exchange rules.

The outcome is the wrong program, the wrong country and the wrong timing. Students struggle in courses that do not suit them. Graduates find no work pathway after the degree. Transfers and restarts cost years and money. Most of all, there is unnecessary stress for the child and for the parents.

None of this is inevitable. Almost all of it is avoidable with earlier advice.

How Ajmera Law International advises UHNI families and family offices

Education and settlement planning. We look at the child first, then the country. We help families choose the right destination, the right program and the immigration pathway that follows, whether that is a student visa leading to a work visa or a longer-term residency route. We map this against the family’s wider business and wealth plans, so that a decision made at 17 does not create a problem at 25.

Residency and citizenship options. For families who want global flexibility for their children, we advise on residency and citizenship by investment programs, EB-5 and other investor routes, and European and Middle East options, including the compliance side of each. The objective is not to collect passports. It is to give the next generation real choices and the family a genuine global footprint.

Global portfolio and business expansion. We work alongside the family’s CA, wealth manager and business advisors to see how overseas residency, foreign entities and international investments can support the expansion of the family business and the creation of a global asset base.

FEMA and cross-border compliance. Funding education abroad, buying property overseas or investing in a foreign program must be structured within FEMA, the Liberalised Remittance Scheme and related regulations. We make sure the money moves correctly, properly documented and defensible, so a good plan does not become a compliance problem later.

Succession and inheritance planning. When children become residents or citizens of other countries, and assets sit in more than one jurisdiction, inheritance questions become complex. Some countries have estate or inheritance tax rules that surprise Indian families. We help structure wills, trusts and succession arrangements that work across borders, and we advise on documents such as the Living Will and Advance Medical Directive so that personal wishes are protected as well.

GIFT City and structured vehicles. For families looking at international structuring within India’s framework, we advise on GIFT City IFSC options as part of the broader plan.

Why timing matters?

The single most useful thing we tell families is this: come to us earlier.

When we are consulted while the child is still in school, or before the family has committed to a country or a program, we have far more options to offer. We can shape the academic path, plan the funding, prepare the residency route and align it all with the family business in the right sequence. When we are consulted after a wrong decision has been made, we can still help, but the choices are narrower and the cost, in money, time and emotional strain, is higher.

A wider future for the family

Good planning for the next generation is not about controlling their future. It is about widening it. When global mobility is treated as part of the family’s business and wealth strategy, it protects the family, builds a global portfolio, supports tax planning and gives the children real options.

With offices in Ahmedabad, USA, Canada and UAE, and a third-generation legal practice that has served over 30,000 clients across more than 20 countries, Ajmera Law International provides one coordinated view for single and multi-family offices.

If you are a UHNI family or a family office thinking about your children’s education abroad, their residency options or the succession of your wealth, we would be glad to speak with you. A first conversation costs little. A wrong decision costs a great deal.

Prashant Ajmera
Founder and Advocate, Ajmera Law International
info@ajmeralaw.com | +91 9974253030 | www.ajmeralaw.com


Prashant Ajmera is a Canadian citizen since 1997, NRI sicne 1988 and  the Founder and Advocate of Ajmera Law International, a cross-border and global mobility law firm based in Ahmedabad with a presence in Cabada, USA and UAE. A third-generation legal practitioner with a B.Sc, LLM and ICSA (UK), he advises UHNI families, family offices and NRIs on residency and citizenship by investment, EB-5, FEMA compliance, GIFT City and cross-border succession planning. He has authored “Millionaires On the Move” and serves as Vice President of the Indo-American Chamber of Commerce (IACC), Ahmedabad and founder of Organ Donation Trust  – OneIndiaOneLaw.org


September 28, 2026

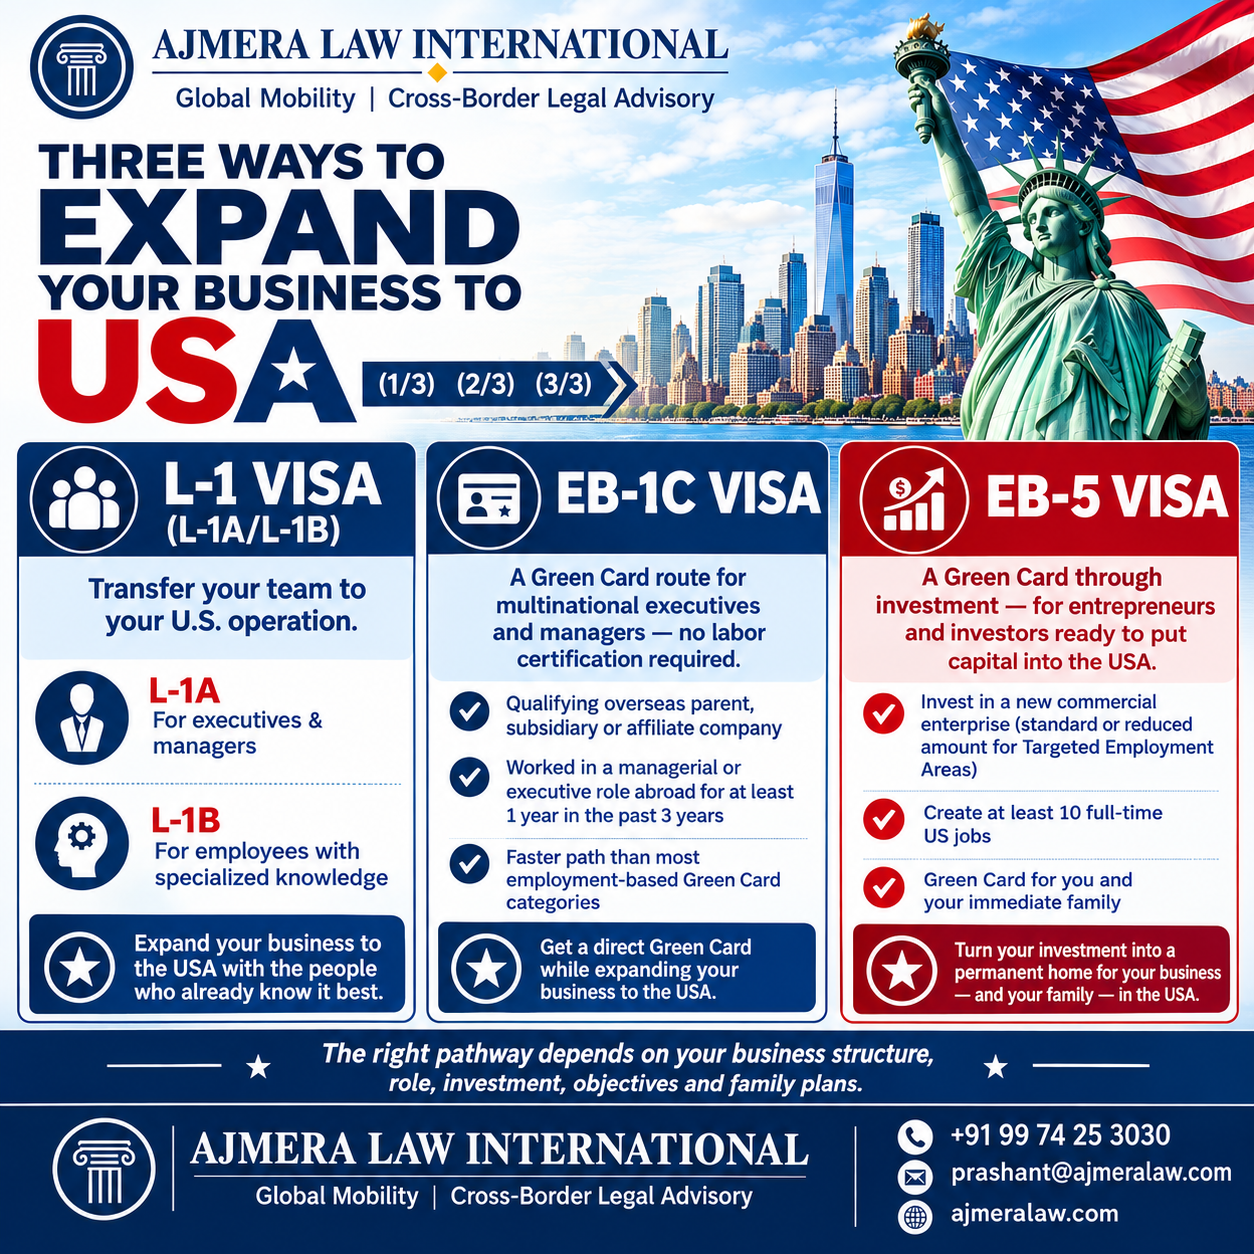
Three Ways to Expand Your Business to the USA

A Guide to Business Immigration Options

For Indian entrepreneurs and business owners, entering the American market is often less about starting from scratch and more about choosing the right legal pathway to move people, leadership, or capital across borders. U.S. immigration law offers several routes for this, but three stand out as the most commonly used by companies looking to establish, grow, or invest in a U.S. presence: the L-1 visa, the EB-1C visa, and the EB-5 visa. Each serves a different purpose, comes with its own eligibility criteria, and leads to different long-term outcomes. Understanding how they differ, and how they can work together, is essential for any business owner planning a serious move into the U.S. market.


1. Expanding Through People: The L-1 Visa

The L-1 visa is designed for companies that already have an established business outside the United States and want to open, run, or grow a U.S. office by transferring their own staff, rather than hiring locally from day one. It is a non-immigrant visa, meaning it is temporary in nature, but it is one of the most flexible and widely used tools for cross-border business expansion because it does not require a labor certification or proof that no qualified American worker is available for the role. The employer simply needs to demonstrate a genuine business need and a qualifying relationship between the overseas company and the U.S. entity.

There are two categories under the L-1 visa. The L-1A is for executives and managers, and covers individuals who will direct the organization, a major function within it, or a team of professional employees. This is typically the category used by business owners themselves, or by senior leadership being sent to establish and run the U.S. operation.

The L-1B is for employees with specialized knowledge, meaning individuals who possess an advanced level of expertise in the company’s products, services, research, systems, or processes that is not commonly found in the broader labor market. This category is often used for technical staff, engineers, or subject-matter experts whose knowledge is critical to setting up or operating the U.S. business.

To qualify for either category, the employee must have worked for the overseas company for at least one continuous year within the three years immediately preceding the application. The overseas and U.S. entities must also have a qualifying relationship, such as parent and subsidiary, affiliate, or branch office, and both entities must be actively doing business, not simply holding an office on paper.

One of the most valuable features of the L-1 visa is the new office provision, which allows a company that does not yet have a functioning U.S. office to still bring over an executive or manager to establish one. In this case, the initial approval is limited to one year, after which the company must show that the U.S. office is operating, generating revenue, and has hired staff, in order to extend the visa further. This makes the L-1 an ideal entry point for businesses that are serious about a U.S. presence but are still in the early stages of building it.

Once approved, the L-1A visa can be extended up to a maximum of seven years, while the L-1B can be extended up to five years. Spouses of L-1 visa holders receive L-2 status, which allows them to apply for work authorization in the U.S., and children can attend school on the same dependent status. Perhaps most importantly for long-term planning, L-1A status creates a natural and efficient bridge to permanent residency, because L-1A executives and managers are the exact profile targeted by the next category: the EB-1C visa.

2. From Transfer to Green Card: The EB-1C Visa

While the L-1 visa is temporary, the EB-1C is an immigrant visa category, meaning it leads directly to a Green Card from India. It is specifically designed for multinational executives and managers who have been working abroad for a company that has a qualifying U.S. affiliate, and who now wish to continue in an executive or managerial capacity for the U.S. entity on a permanent basis.

The eligibility requirements mirror those of the L-1A in many respects. The applicant must have worked in a managerial or executive role abroad for at least one year within the three years before filing, and there must be a qualifying relationship between the U.S. company and the overseas entity. The U.S. company must also have been doing business for at least one year at the time of filing. Because of this overlap, the EB-1C is often pursued as the natural next step after an individual has spent time in the U.S. on an L-1A visa, having already demonstrated that the U.S. office is functioning and that the executive role is genuine.

What makes the EB-1C particularly attractive compared to most other employment-based Green Card categories is that it does not require labor certification. Most employment-based immigrant visas require the employer to first test the U.S. labor market and obtain a certification from the Department of Labor showing that no qualified American worker is available for the position. This process, known as PERM, can take well over a year on its own. The EB-1C skips this step entirely, which significantly shortens the overall timeline and reduces administrative burden, making it one of the more efficient employment-based Green Card routes available.

That said, processing times for EB-1C petitions are still subject to the U.S. visa bulletin, which allocates a limited number of Green Cards each year by country of birth. Applicants born in countries with high demand, notably India, may experience longer waiting periods for their priority date to become current, even after the petition itself is approved. This is an important planning consideration, and one where early filing can make a meaningful difference over time.

The outcome of a successful EB-1C petition is significant: a direct, permanent Green Card for the applicant, along with the applicant’s spouse and unmarried children under 21. There is no need to first hold a temporary L-1 visa to qualify for EB-1C, though in practice, many successful applicants do use the L-1A as a stepping stone, since it allows the U.S. business to establish a track record before the permanent petition is filed.

3. Building a Presence Through Capital: The EB-5 Visa

The third major route, and the one most distinct from the other two, is the EB-5 visa. Rather than being based on an employment relationship or a transfer of personnel, the EB-5 is an investment-based Green Card category. It is designed for individuals who are willing to invest a significant amount of capital into a new commercial enterprise in the United States and, in doing so, create jobs for American workers.

The minimum investment threshold depends on the location of the project. For investments made in a Targeted Employment Area, meaning a rural area or a region with high unemployment, the required investment is 800,000 US dollars. For projects outside a Targeted Employment Area, the standard investment amount is 1,050,000 US dollars. In either case, the investment must be at risk, meaning it must be placed into a genuine commercial enterprise with the potential for gain or loss, rather than simply parked in a safe or guaranteed instrument.

The central requirement of the EB-5 program is job creation. The investment must directly or indirectly create or preserve at least ten full-time jobs for qualifying U.S. workers within a defined period. There are two broad ways to meet this requirement. The first is direct investment, where the investor starts or invests in their own business and is directly responsible for creating the required jobs. The second, and by far the more common route among Indian investors, is investment through a Regional Center, which is a USCIS-designated entity that manages larger development projects and pools capital from multiple investors. Regional Center investments allow for a more passive role, since job creation can be counted using indirect and induced employment models, and the investor is not required to be involved in the day-to-day management of the business.

Because EB-5 does not require the investor to work for or manage the enterprise personally, it is often the preferred route for business owners, professionals, or families who want a Green Card primarily for lifestyle, education, or long-term security reasons, rather than to actively operate a U.S. business themselves. It is worth noting, however, that EB-5 approval is initially conditional. Investors and their families receive a two-year conditional Green Card, and must later file a petition to remove the conditions by demonstrating that the required jobs were, in fact, created and that the investment remained at risk throughout the required period.

Like the EB-1C, EB-5 approval extends to the investor’s spouse and unmarried children under 21, making it a strong option for families planning a long-term move. Unlike the L-1 and EB-1C categories, EB-5 does not require any employer sponsorship at all. The investor is entirely self-sponsored, which removes the dependency on an existing overseas business or employment relationship, and opens the door to individuals who may not have a company to transfer staff from, but do have the capital to invest.

Choosing the Right Path

Each of these three categories serves a different kind of business goal. The L-1 visa is best suited to companies that already have an operating business abroad and want to move their own people to establish or grow a U.S. presence, with a realistic path to later convert that presence into a permanent Green Card through EB-1C. The EB-1C is the natural long-term destination for executives and managers who have proven, often through the L-1, that their U.S. operation is genuine and functioning. The EB-5, by contrast, does not depend on an existing business or employment history at all, and instead offers a direct route to permanent residency through capital investment and job creation, making it especially attractive to investors and families seeking a more passive path to a U.S. Green Card.

For many businesses, these routes are not mutually exclusive but sequential. A company might begin with an L-1 visa to establish its U.S. office, and once that office is operating successfully, its executive can pursue an EB-1C Green Card. Alternatively, a business owner without an existing company structure suited to L-1 or EB-1C may find that EB-5 offers the most direct path to permanent U.S. residency for the entire family.

Given the complexity of eligibility requirements, documentation, and processing timelines involved in each of these categories, working with experienced legal counsel from the outset is essential to choosing the right strategy and avoiding costly delays.

4. Bonus Path

There is also a fourth possibility, distinct from all three immigration routes above, for Indian HNIs and UHNIs who want to invest in the United States purely for financial reasons, with no visa or residency expectation attached. This route is suited to investors seeking higher returns, geographic diversification of their portfolio, and a way to build a corpus for their children’s future education abroad. The investment could be in land, real estate or financial market.


Ajmera Law International advises businesses and individuals on global mobility and U.S. business immigration strategy, including L-1, EB-1C, and EB-5 matters.

Contact: Advocate Prashant Ajmera

+91 9974253030  |  prashant@ajmeralaw.com  |  ajmeralaw.com

September 15, 2026

₹2.5 Crore: Your Second Home in Greece

Access 27 EU Countries & Unlock a World of Possibilities for Your Family

By Prashant Ajmera | Advocate & Immigration Lawyer | Ajmera Law International

Introduction: The €250,000 Question

Imagine owning a premium apartment on the Mediterranean coast, holding a European Union Residence Permit, travelling visa-free across 27 Schengen countries, and securing a citizenship pathway for your children — all for approximately ₹2.5 Crore. This is not a distant dream. This is the Greece Golden Visa in 2026.

For Indian investors, NRIs, business families, and high-net-worth individuals, the Greece Golden Visa has emerged as the most strategically compelling residency-by-investment programme in Europe today. It combines the lowest entry threshold in the EU with zero relocation requirements, a robust real estate market, and a path to one of the world’s most powerful passports.

In this article, we explore every dimension of what this investment unlocks — from your child’s education to your own retirement — and walk you through every legal route available to make Greece your second home.

Why Greece? Why Now?

Greece sits at the crossroads of Europe, Asia, and Africa. It is a member of the European Union, the Schengen Area, and NATO. With over 6,000 islands, a 16,000-kilometre coastline, 250+ days of sunshine annually, and a deeply established tourism economy, Greece offers an unmatched quality of life.

But beyond lifestyle, Greece presents a rare economic window. After a decade of economic recovery, property values in Athens and key tourist destinations are rising steadily, rental demand is at an all-time high, and the government has actively structured its Golden Visa programme to attract foreign investment.

For Indians specifically, the Greece Golden Visa solves a cluster of real-life challenges that no other single programme addresses simultaneously.

One Investment. Seven Problems Solved.

1. Your Child’s Foreign Education

Every aspirational Indian family wants the best global education for their children. With a Greek EU Residence Permit, your child gains access to European universities at EU-domestic tuition fees — a fraction of international student fees. Greece After completing education in Europe, your child has the right to work and build a career across the EU — a generational advantage that no Indian visa or temporary permit can offer.

2. Business Expansion Into Europe

Greece is a gateway into the EU single market — the largest trading bloc in the world with over 450 million consumers. As a Greek resident, you can register a company in Greece, open EU bank accounts, access European funding schemes, and conduct business freely across all 27 member states without separate visas or work permits.

For Indian exporters, manufacturers, IT companies, and service businesses looking to establish a European base, a Greek residence combined with a local entity offers the most cost-effective and legally compliant structure available.

3. Visa-Free Travel Across 29 Schengen Countries

The Greek Golden Visa Residence Permit grants you and your entire family visa-free movement across all 29 Schengen Area countries — including France, Germany, Italy, Spain, Netherlands, Switzerland, and more.

For business travellers, frequent flyers, and families with education or lifestyle interests across Europe, this alone represents enormous practical and financial value. No more long visa queues, appointment delays, or last-minute rejections.

4. Quality of Life — Mediterranean Living

Greece consistently ranks among the top 10 countries globally for quality of life. With world-class healthcare, clean environment, outstanding cuisine, a rich historical legacy, and a relaxed Mediterranean pace of life, Greece offers something that no balance sheet can fully capture.

5. Tax Planning Opportunities

Greece offers one of Europe’s most attractive flat-tax regimes for new residents. Under the Non-Domicile Tax Programme, qualifying new residents can pay a flat annual tax of €100,000 on all foreign-sourced income — regardless of the actual amount earned abroad. This is a significant planning tool for high-income NRIs and business owners with global income streams.

Additionally, Greece has signed Double Taxation Avoidance Agreements (DTAA) with India and numerous other countries, offering structured relief from dual taxation on income, dividends, and capital gains.

6. Retirement Planning

Greece is one of the most sought-after retirement destinations in the world. The cost of living is significantly lower than Western Europe — healthcare is excellent, food is fresh and affordable, and the pace of life is gentle. For Indian retirees or pre-retirees planning their global lifestyle, owning property in Greece while holding an EU residence permit is the gold standard of retirement planning abroad.

7. Portfolio Diversification

Sophisticated investors understand the risk of concentrating wealth in a single geography or currency. A Greek real estate asset denominated in Euros provides natural diversification against INR depreciation, Indian market volatility, and domestic real estate cycles.

With rental yields of 4–7% annually in prime tourist zones and steady capital appreciation in Athens and island markets, Greek real estate is both a lifestyle asset and a performing financial investment.

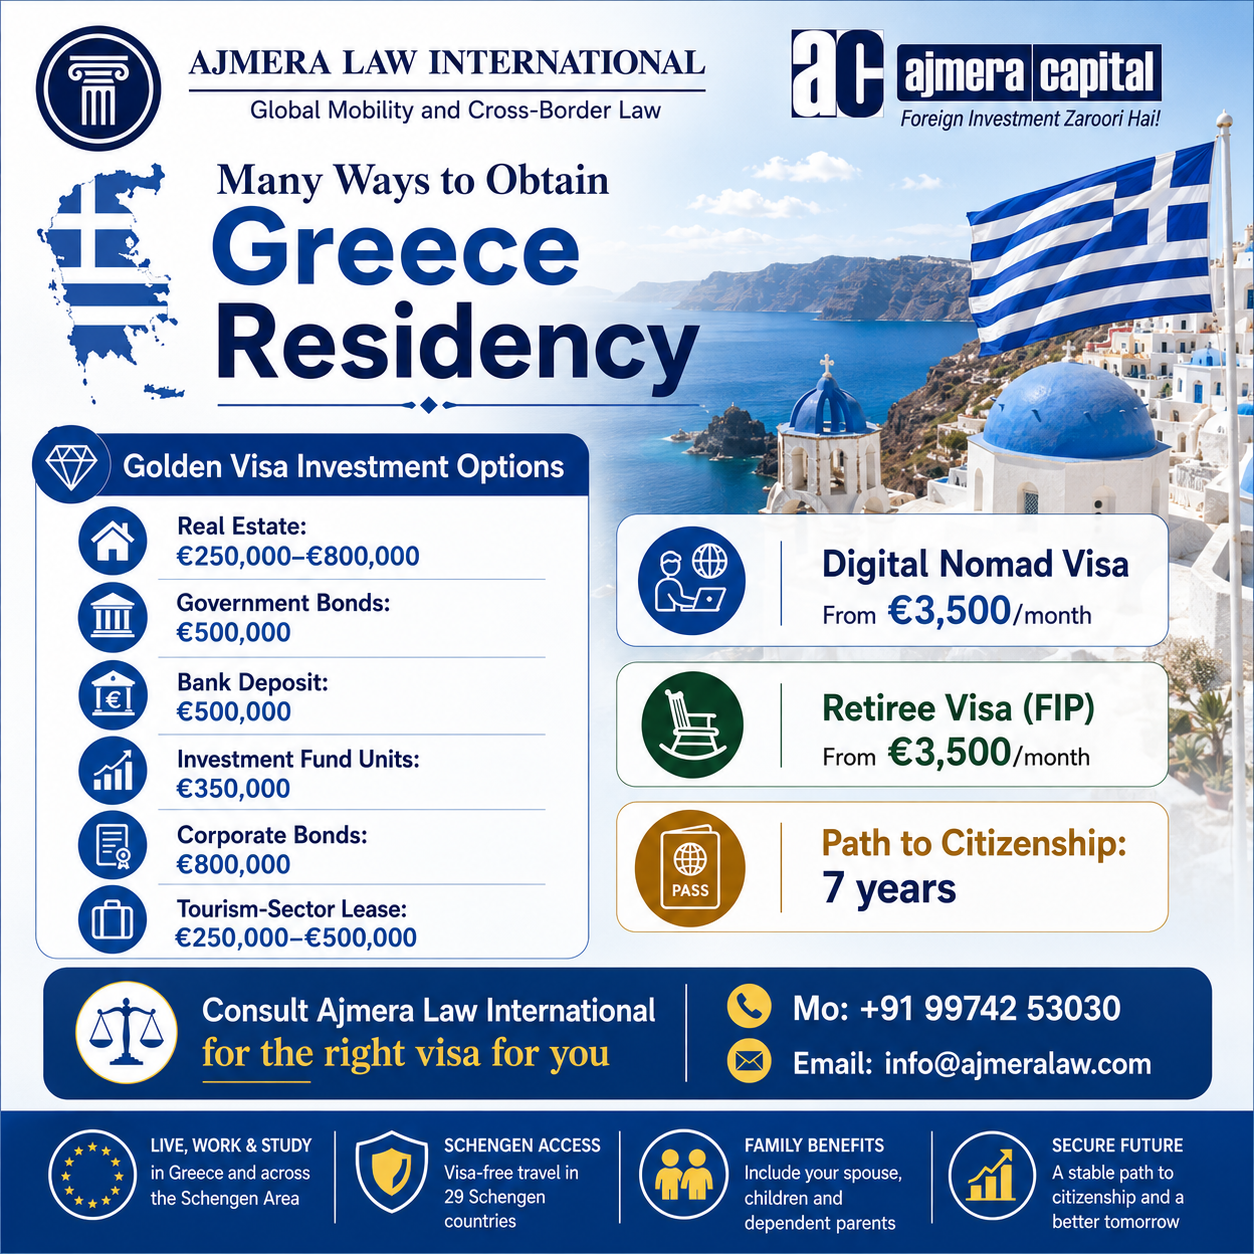
Greece Golden Visa: All Investment Routes (2026)

The Greece Golden Visa programme offers multiple investment pathways. Each route delivers the same core benefit — a 5-year renewable EU Residence Permit — but differs in investment amount, asset type, and risk profile.

Route 1 — Real Estate Investment (Most Popular)

Investment Thresholds:

  • €250,000 — Conversion or restoration of listed historic buildings or industrial buildings. Special category available across Greece.
  • €400,000 — Residential or commercial property in mainland Greece and smaller islands (population under 3,100).
  • €800,000 — Properties in high-demand areas: Athens, Thessaloniki, Mykonos, Santorini, and other major islands.

Real estate investment remains the most popular route as it combines residency with a tangible, income-generating asset. The property can be rented out while you hold your residence permit. A single property or multiple properties can be combined to meet the threshold. The permit is renewable every 5 years as long as the investment is maintained.

Route 2 — Capital Investment in Greek Companies or Funds

  • €500,000 minimum investment in shares, corporate bonds, or Greek Government bonds held through a Greek financial institution.
  • €350,000 minimum investment in units of AIF (Alternative Investment Funds), REITs, or venture capital funds established and operating in Greece.
  • €500,000 investment in a Greek company with a registered office in Greece, creating at least one full-time job.

Capital investment routes are ideal for investors who prefer managed funds over direct property ownership, or who seek investment diversification across Greek business sectors. These routes carry market risk but offer professional management and potential capital growth.

Route 3 — Time Deposit in Greek Bank

A minimum deposit of €500,000 in a Greek bank account as a fixed-term deposit for at least one year, with an automatic renewal obligation. This is the most capital-safe route, though it generates lower returns compared to real estate or equity investment.

Route 4 — Investment in Innovative Startups

Investors may qualify through a minimum investment of €250,000 in innovative startup companies registered with the Greek Startup Registry (Elevate Greece). This route appeals to investors with an interest in technology, entrepreneurship, and early-stage business ventures in the Greek innovation ecosystem.

Greece Digital Nomad Visa — Work From Paradise

Greece introduced its Digital Nomad Visa in 2021, making it one of the first EU countries to formally welcome remote workers and location-independent professionals from non-EU countries, including India.

Key Features:

  • Eligibility: Non-EU nationals who work remotely for foreign employers or clients — not for Greek companies or clients.
  • Minimum income requirement: Approximately €3,500 per month net (subject to revision).
  • Initial permit duration: 1 year, renewable for 2 years at a time.
  • Schengen access during the permit period.
  • Family members may accompany the primary applicant under separate permits.
  • 50% income tax exemption for the first 7 years for qualifying digital nomads who establish tax residency in Greece.

The Digital Nomad Visa is ideal for Indian IT professionals, consultants, freelancers, and entrepreneurs who work with international clients and wish to enjoy the Greek lifestyle without making a large capital investment. It does not lead directly to permanent residency or citizenship, but long-term stays can eventually build towards residency rights.

Greece Retirement Visa — Your Golden Years in Europe

Greece offers a specific long-stay visa pathway for retirees from non-EU countries who wish to reside in Greece without working. This visa, combined with Greece’s flat-tax regime for retirees, makes it one of Europe’s most attractive retirement destinations.

Key Features:

  • Eligibility: Non-EU nationals with a stable passive income from pensions, investments, rental income, or other foreign sources.
  • Minimum income: Approximately €2,000 per month for the applicant, plus €200 per additional family member.
  • Must have valid health insurance coverage in Greece.
  • Must have rented or owned accommodation in Greece.
  • Flat 7% tax on all foreign-sourced income for the first 10 years under Greece’s Non-Domicile Retiree Tax Programme.
  • Permit valid for 2 years, renewable. Long-term residency after 5 years of continuous stay.

For Indian senior professionals, retired business owners, or NRIs drawing pension or investment income from abroad, this programme offers a legally sound, tax-efficient, and lifestyle-rich retirement structure in Europe without the need for a large capital investment.

Path to Greek Citizenship — The Ultimate Goal

The Greek passport is one of the most powerful travel documents in the world — providing visa-free or visa-on-arrival access to over 185 countries, including the USA, UK, Canada, Australia, Japan, and all EU member states. For Indian nationals, Greek citizenship represents a transformational upgrade in global mobility and opportunity.

Citizenship Route via Golden Visa:

  • After 7 years of legal residence in Greece (including time under the Golden Visa), investors can apply for Greek citizenship by naturalisation.
  • The applicant must demonstrate physical presence — spending meaningful time in Greece (not just holding the permit).
  • Greek language proficiency (A2 level) is required for the naturalisation examination.
  • Clean criminal record and integration into Greek society are assessed.
  • Children born to Greek permanent residents may have separate, accelerated pathways to citizenship.

Important Note on Indian Law:

India does not permit dual citizenship. Upon acquiring Greek citizenship, Indian nationals are required to surrender their Indian passport and apply for an OCI (Overseas Citizen of India) card, which provides near-citizen benefits in India without voting rights. This is a critical decision that requires careful legal and personal planning, ideally undertaken with specialist immigration and FEMA counsel.

Conclusion: ₹2.5 Crore That Works on Multiple Levels

The Greece Golden Visa is not simply a visa. It is a long-term strategic decision that simultaneously solves your family’s education needs, your business expansion ambitions, your travel freedom, your retirement comfort, your tax efficiency, and your portfolio diversification — all anchored in a real asset in one of the world’s most beautiful countries.

At ₹2.5 Crore — the price of a mid-range apartment in Mumbai or Ahmedabad — you can own a premium waterfront property in Athens, hold an EU Residence Permit, access 29 Schengen countries without a visa, and set your family on a path to a Greek passport.

The question is no longer whether Greece makes sense. The question is: how soon will you act?

August 15, 2026

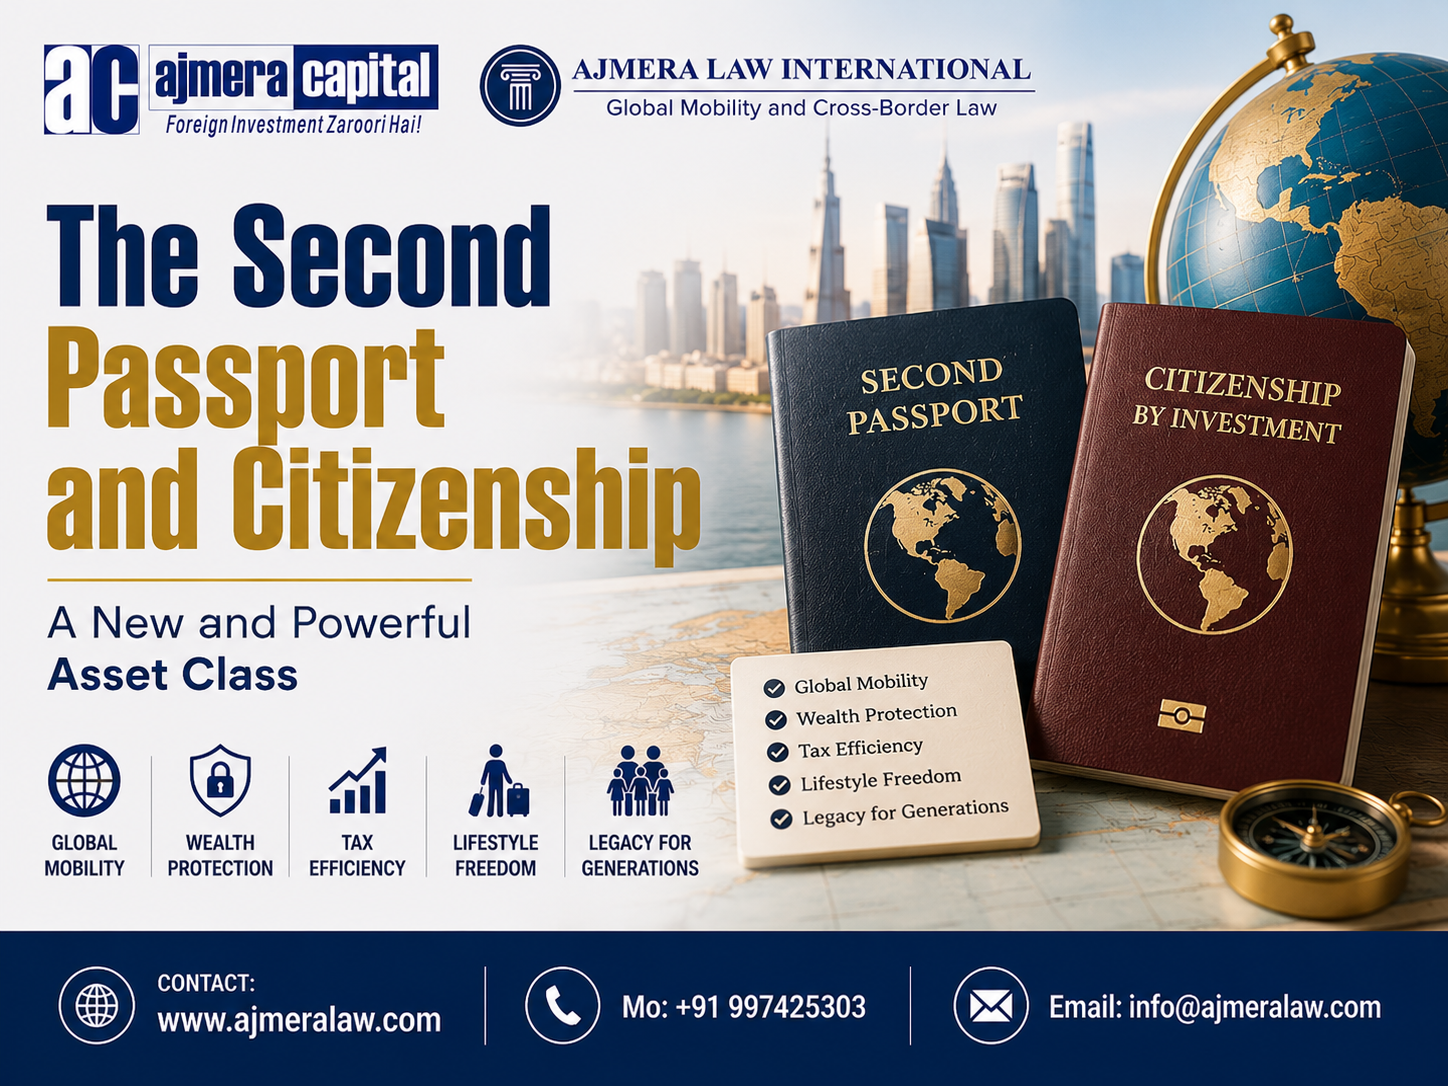
The Second Passport:  A New and Powerful Asset Class


Investment, in its simplest sense, is the act of putting capital to work today in exchange for a financial return tomorrow — without trading your time or labour for it. The larger the return, the larger your net worth grows, and the more freedom you have to pursue the life you want.

But not every high-value investment is measured only in returns. Some investments do not promise the highest yield on paper — yet they hand you something money alone cannot always buy: the right to live, work, study, and belong in another country. Residency and citizenship by investment have quietly become one of the most versatile asset classes available to globally-minded individuals and families today. They don’t just diversify a portfolio — they diversify a life.

Consider the range of situations where a second residency or passport delivers value no traditional asset can match:

  1. The businessman expanding overseas

An entrepreneur looking to take his business beyond his home country often starts with imports and exports. But as the business grows, he may need a physical presence abroad. Residency by investment lets him operate as a local company — with all the advantages, credibility, and market access that status brings, rather than functioning as a foreign entity.

  1. Parents planning their children’s education

Indian parents in their mid-thirties with school-going children often look years ahead to global university. If the family qualifies for residency — and eventually citizenship — of the right country, the savings can be dramatic: tuition fees can drop by as much as 80% in countries like Canada, disappear altogether in parts of Europe, and fall sharply under in-state rates in the United States.

  1. The HNI optimising personal tax

A high-net-worth Indian who obtains citizenship — and establishes domicile — in another jurisdiction may be able to restructure and reduce personal tax liability as part of a broader, well-advised wealth plan.

  1. The young athlete with global ambitions

For a young sportsperson seeking training at a European Union academy, a Golden Visa, retiree visa, or nomad visa for accompanying parents can be the key that unlocks access to world-class facilities and coaching.

  1. The frequent traveller

For those who travel constantly for business or leisure, visa applications for every trip become a friction point. An EU residency — obtained through real estate or other qualifying financial instruments, which vary by country — removes that friction entirely.

  1. The start-up founder going global

Founders looking to scale internationally can use residency or citizenship from more than 30 countries as a strategic lever for global expansion — opening doors to new markets, banking systems, and talent pools.

  1. The HNI diversifying beyond markets

Just as a smart investor diversifies across asset classes, a high-net-worth individual should consider residency or citizenship in another country to diversify against geopolitical and economic risk — a hedge no stock or bond can offer.

  1. The retiree seeking the best of both worlds

Retirees and HNIs with steady passive income can look at European retiree visa programmes to enjoy quality of life, healthcare, and stability abroad while retaining ties to home.

  1. The multinational relocating talent

When a multinational acquires a business abroad, the acquisition can also qualify senior executives for residency in the new country — enabling them to manage and grow operations from within.

A Quick World Tour: Popular Residency & Golden Visa Routes

Programme rules and investment thresholds change frequently — the snapshot below reflects the general shape of each route and should be verified against current regulations before any decision is made.

United States — EB-5 Immigrant Investor Programme

A minimum investment of USD 800,000 in a Targeted Employment Area (or USD 1.05 million elsewhere) through a qualifying project that creates at least ten full-time jobs. Investors and their immediate family receive a US Green Card, with eligibility for citizenship after five years of permanent residency.

Canada — Provincial and Start-up Routes

Canada’s federal Immigrant Investor Programme has closed, but Provincial Nominee Programmes remain active pathways for entrepreneurs and investors. Requirements vary by province and typically combine a qualifying investment or business plan with job-creation or innovation criteria.

Portugal — Golden Visa

Since the 2023 reform, the real estate route is closed; qualifying options now include fund subscriptions (from EUR 500,000), capital transfer (EUR 1.5 million), or job creation and cultural/research donations from EUR 250,000. Just seven days of stay per year is required, with a path to citizenship after five years.

Greece — Golden Visa

Following the 2023–24 revision, real estate thresholds now stand at EUR 250,000 or EUR 800,000 in Athens, Thessaloniki and popular islands, and EUR 400,000 elsewhere. The permit is renewable with minimal physical presence required, though it does not by itself lead to citizenship.

Latvia — Investor Residence Permit

Available through real estate investment from EUR 250,000, a qualifying business investment, or a government bond/bank deposit route. Renewal now carries stricter conditions than in earlier years, so applicants should review current requirements closely. Also Euro 50,000 or 100,000 options is available for businessmen who can generate business and create jobs.

Malta — MPRP and Citizenship by Naturalisation

The Malta Permanent Residence Programme combines a government contribution, real estate (purchase or lease) and a donation, totalling roughly EUR 150,000–300,000. Malta also retains a direct Citizenship by Naturalisation for Exceptional Services route — one of the few in the EU — requiring a substantially higher contribution alongside real estate and due-diligence review.

Cyprus — Permanent Residency

Cyprus an English speaking country in EU discontinued its citizenship-by-investment scheme in 2020, but its Permanent Residency Programme remains open through real estate investment of EUR 300,000 or more, offering fast-track approval and visa-free Schengen-area travel privileges do not apply, though EU residency benefits do.

Bulgaria — Investor Residence

Bulgaria’s accelerated citizenship-by-investment track was abolished in 2022. Standard investor residence permits are still available through qualifying business or capital investment, though the route to citizenship is now considerably longer.

Spain — Post-Golden Visa Landscape

Spain’s Golden Visa programme was abolished in April 2025 and no longer accepts real estate-based applications. Investors are instead exploring the Non-Lucrative Visa and Digital Nomad Visa as alternative long-term residency routes.

Italy — Investor Visa

Italy offers a menu of options: EUR 2 million in government bonds, EUR 500,000 in an Italian company, EUR 250,000 in an innovative start-up, or a EUR 1 million philanthropic donation. The permit is renewable, with citizenship available after ten years of legal residence.

The Caribbean — Citizenship by Investment

St Kitts & Nevis, Antigua & Barbuda, Dominica, Grenada and St Lucia each run long-standing Citizenship by Investment programmes, typically via a government donation from around USD 200,000 or a real estate investment from USD 200,000–400,000. Processing is fast (often three to six months), there is no residency requirement, and citizenship brings visa-free access to well over a hundred countries.


The bottom line: A second passport or residency is no longer a luxury reserved for the ultra-wealthy or a matter of convenience for frequent flyers. It is a strategic, multi-generational asset — one that hedges risk, unlocks education and business opportunity, optimises tax exposure, and above all, buys optionality. In a world of shifting borders and policies, that may be the most valuable return of all.

Prashant Ajmera is the Founder of Ajmera Law International (ALI), a cross-border and global mobility law firm headquartered in Ahmedabad with a presence in Dubai, USA, EU and C

July 15, 2026

The Living Will: India’s Most Ignored Wealth Document

You have a Will for your assets. You have a succession plan for your business. You have a trust for your grandchildren. But there is one legal document — legally valid in India since 2018, recognised by the Supreme Court of India, and capable of determining whether you live or die on a ventilator — that not a single member of your wealth advisory team has ever placed before you. It is called an Advance Medical Directive. The world knows it as a Living Will. And for India’s HNI and UHNI community, it may be the most consequential document you have never signed.

The Blind Spot in India’s Wealth Planning Ecosystem

Walk into the office of any top private bank, family office, or independent financial advisor in India today. You will find sophisticated conversations about portfolio construction, estate planning, succession law, offshore trusts, and inter-generational wealth transfer. What you will almost certainly not find is any conversation about what happens when the client — not the portfolio, not the business — becomes incapacitated.

This is not a minor oversight. It is a systemic blind spot.

The financial industry in India has, understandably, focused its advisory infrastructure on the accumulation and transfer of wealth. The entire architecture of wealth management — from portfolio management services to SEBI-registered investment advisers to private wealth divisions of global banks — is oriented around financial instruments, tax efficiency, and asset protection.

What falls entirely outside this architecture is the question of medical decision-making. And for HNIs and UHNIs, the stakes of this omission are enormous.

When a high-net-worth individual is struck by a sudden medical crisis, the vacuum of legal authority over medical decisions can be as catastrophic as the absence of a Will.

Consider a scenario familiar to any senior medical practitioner in India: a 68-year-old founder of a Gujarat-based industrial group suffers a severe stroke. He is in the ICU, unconscious, and incapable of communicating. The attending doctors face an immediate decision about aggressive life-sustaining treatment. The family — adult children with divergent views, a spouse in acute distress, a business partner with his own interests — cannot agree. There is no legal document that speaks for the patient.

In this vacuum, the doctors default to maximum intervention: every machine, every procedure, every month of ICU care — regardless of what the patient may have wished. The costs mount into crores. The dignity of the patient’s final period of life is entirely surrendered. And critically: not one rupee of the family’s carefully structured estate plan addresses this moment.

This is precisely the problem a Living Will — or in Indian legal terminology, an Advance Medical Directive (AMD) — is designed to solve.

What Is a Living Will? The Indian Legal Framework

The term ‘Living Will’ is widely used globally, but its Indian legal avatar carries a specific name and a specific statutory foundation. Under the Mental Healthcare Act, 2017 (MHA 2017) — which came into force on May 29, 2018 — every adult Indian citizen of sound mind has the right to make an Advance Directive specifying their wishes regarding medical treatment in advance.

This right was emphatically affirmed — and its constitutional legitimacy confirmed — by the Supreme Court of India in its landmark constitutional bench judgment in Common Cause v. Union of India, (2018) 5 SCC 1, delivered on March 9, 2018. A five-judge bench, speaking in five separate concurring opinions, unanimously held that the right to refuse unwanted medical treatment is an intrinsic element of the right to life and personal liberty under Article 21 of the Constitution.

In simple terms: you have the right, as a legally competent adult, to decide in advance what medical interventions you do and do not want if you ever lose the capacity to make or communicate decisions. That decision, made in writing, signed, witnessed, and registered before a Judicial Magistrate First Class, constitutes a legally enforceable Advance Medical Directive.

The key legal facts every HNI and their advisors should know:

Governing Law The Mental Healthcare Act, 2017 (MHA 2017)
Effective Date of MHA May 29, 2018
Document Name in Law Advance Medical Directive (AMD) / Advance Directive
Who Can Execute? Any person above 18 years, of sound mind
Registration Before a Judicial Magistrate First Class (JMFC)
Witnesses Required Two independent witnesses present at signing
Medical Counterpart Medical Board of at least 3 doctors must concur
Revocation May be revoked at any time by the maker
Nominated Representative Healthcare proxy who speaks for you if incapacitated
Supreme Court Ruling Common Cause v. Union of India, (2018) 5 SCC 1

Why This Is a Wealth Planning Issue, Not Just a Medical One

The financial advisory community has, by and large, treated the Living Will as a medical or bioethical matter — interesting, perhaps, but outside the scope of a wealth management conversation. This framing is both understandable and deeply mistaken.

The Financial Cost of Unplanned ICU Care

India’s top private hospitals now charge between Rs. 1 lakh and Rs. 3 lakh per day for ICU care involving advanced life support. A prolonged period of futile treatment — keeping a patient alive in a persistent vegetative state, or with no realistic prospect of recovery — can consume Rs. 50 lakh to Rs. 5 crore or more over weeks and months. These are not theoretical figures. They are documented in the case histories of families who spent their inheritance on ventilators.

For UHNI families with international assets, the costs compound dramatically. Medical evacuation to Singapore or the UK, followed by ICU care at $3,000–$10,000 per day, can trigger financial consequences that dwarf the premiums of any health insurance policy the family holds.

An Advance Directive — by clearly specifying under what conditions the patient does not wish to receive life-sustaining treatment — can prevent this financial catastrophe entirely. It converts a blank cheque of unbounded liability into a defined, dignified, and legally authorised plan.

The Succession and Estate Planning Dimension

Every estate planning lawyer knows that the period of incapacity — the gap between the moment a person loses capacity and the moment they die — is the most legally turbulent period in any succession. In the absence of a Living Will:

  • Family members may need to approach courts for guardianship orders, at significant legal cost and reputational exposure.
  • Business succession plans may be disrupted if the founder or key decision-maker is incapacitated without a designated healthcare proxy who understands the business context.
  • Trusts and estate structures with testamentary instructions may be effectively frozen if the trustee or settlor is in a medically incapacitated state without legal documentation covering that scenario.
  • Family disputes over medical decisions — which hospital, which doctor, which treatment — can fracture family relationships precisely at the moment when family unity is most needed for wealth management.

A properly structured AMD, combined with a healthcare proxy designation (the Nominated Representative under MHA 2017), inserts a legally authorised voice into this turbulence. That voice speaks not for the hospital, not for the government, and not for whichever family member is loudest — but for the patient.

The Cross-Border Dimension for Global HNIs

For India’s internationally mobile HNI community — Canadian PRs, UK residents, UAE Golden Visa holders, US Green Card holders, or simply frequent travellers — the Living Will question becomes multilateral. A medical emergency in Singapore operates under Singapore law. An incapacitation in the United Kingdom invokes the Mental Capacity Act 2005. A hospitalisation in the UAE requires engagement with the local healthcare regulation authority.

Competent cross-border wealth planning now requires that clients maintain jurisdiction-specific advance directives — or at minimum, an international version that can be accepted or translated across multiple legal systems. This is a space that barely exists in India’s advisory market today, which is precisely why it represents both a gap and an opportunity.

For India’s globally mobile UHNI community, a single country Living Will is no longer sufficient. Medical incapacity does not respect visa categories.

The Supreme Court Watershed: What Common Cause Means

No understanding of the Indian Living Will landscape is complete without engaging seriously with Common Cause v. Union of India, (2018) 5 SCC 1. This is not merely a medical law case. It is one of the most significant constitutional judgments of the post-2010 era, and it has direct implications for wealth and estate planning.

The Supreme Court in Common Cause recognised three critical principles:

  • The right to die with dignity is a fundamental right under Article 21 of the Constitution of India. A person has the right to refuse medical treatment, including life-sustaining treatment, that they do not wish to receive.
  • Passive euthanasia — the withdrawal of life support in defined circumstances — is legally permissible in India, subject to a structured process involving a Medical Board and judicial oversight.
  • An Advance Medical Directive, made while the person is of sound mind, is the authoritative expression of that person’s autonomous choice, and must be respected by medical practitioners, hospitals, and family members alike.

The Court also acknowledged the procedural complexity it had created, and in 2023, it simplified the registration process in response to widespread concerns that the original procedure was too cumbersome. As of the amended guidelines, the AMD can now be registered before a notary and need not require a JMFC in all cases — though the original procedure remains valid. Legal counsel should advise clients on the current operative process in their jurisdiction.

What Common Cause definitively settled is that the Living Will is not a grey area. It is black-letter constitutional law. Any physician, hospital, or family member who ignores a valid AMD may be acting in violation of a fundamental right. That is a statement with direct legal and financial consequences.

Key Takeaway for Wealth Advisors

A Living Will is not a soft lifestyle document. It is a constitutionally grounded legal instrument upheld by a five-judge bench of the Supreme Court of India. Ignoring it in a comprehensive wealth plan is not a conservative approach — it is an oversight with potentially irreversible consequences for your client’s estate, health, and family.

The Five Questions Every HNI Should Ask — and Most Cannot Answer

Here is a simple diagnostic that any financial advisor can pose to a client in the next meeting:

  • If you are ever in a coma with no realistic prospect of recovery, do you want to be kept alive on a ventilator indefinitely? Yes or No?
  • If you lose the ability to communicate permanently, who has the legal authority to speak for you on medical matters — and do they have a document that says so?
  • If you are hospitalised abroad and incapacitated, does your estate plan include any mechanism for foreign medical decision-making?
  • Have you ever discussed with your family — on the record, in a legally witnessed format — what you consider a meaningful quality of life?
  • If you are unconscious in an ICU for six months, what is the total financial liability exposure to your estate, and who bears it?

The overwhelming majority of India’s wealthiest individuals — people whose financial affairs are managed with extraordinary sophistication — cannot answer these five questions with any legal certainty. Their wills are in order. Their trusts are structured. Their offshore accounts are compliant. But when it comes to the most basic question of what happens to them as human beings in a medical emergency, there is silence.

That silence is not philosophical. It is a legal and financial vulnerability.

What an Advance Medical Directive Actually Contains

A well-drafted AMD for an Indian HNI is not a one-page wish list. It is a substantive legal document that typically addresses:

  • Trigger conditions: The specific medical circumstances under which the directive activates — typically including terminal illness with no reasonable prospect of recovery, persistent vegetative state, and end-stage organ failure.
  • Treatment refusal instructions: Specific treatments the person does not wish to receive, such as cardiopulmonary resuscitation (CPR), mechanical ventilation, dialysis, artificial nutrition, or invasive surgical intervention in futility contexts.
  • Treatment consent instructions: Circumstances in which the person affirmatively consents to specific treatments, including palliative care, pain management, and comfort-focused care.
  • Nominated Representative: A designated healthcare proxy — typically a spouse, adult child, or trusted friend — with the authority to speak for the patient when they cannot speak for themselves. This person must be of sound mind, above 18, and willing to accept the responsibility.
  • Medical professional guidance: Instructions to the attending physician, the hospital medical board, and any ethics committee regarding the interpretation of the document.
  • Revocation clause: A statement of the person’s right to revoke or amend the AMD at any time while they retain capacity.

For UHNIs with international exposure, the document should also include a statement of the person’s habitual residence and nationality, a clause addressing cross-border applicability, and ideally a coordinated parallel document under the law of the relevant foreign jurisdiction.

The legal quality of the AMD matters enormously. A poorly drafted document — ambiguous trigger conditions, undefined clinical terms, a Nominated Representative with no guidance on how to exercise their authority — is worse than no document at all, because it creates the illusion of legal protection without the substance.

The Role of the Wealth Advisor: An Untapped Conversation

The question is not whether India’s HNI clients need Living Wills. They do. The question is who facilitates that conversation.

At present, the conversation falls into a gap between professions. The family physician does not consider it their role to raise legal documents. The estate planning lawyer may mention it briefly in the context of a comprehensive succession plan but rarely has the medical literacy to draft it properly. The financial planner does not consider it their domain at all. And the client — faced with the psychological discomfort of confronting their own mortality — rarely initiates the conversation themselves.

This gap is an opportunity for forward-thinking advisors who are willing to take a genuinely holistic view of their clients’ needs. The advisor who introduces the Living Will conversation is not venturing into unfamiliar territory — they are completing the wealth planning picture. They are the advisor who gets the conversation that counts.

The AMD conversation also opens doors that are otherwise closed. It leads naturally to a deeper engagement with the client’s values — their conception of a good life, their views on medical intervention, their family dynamics, their international mobility, and their long-term intentions. These are the conversations from which enduring advisory relationships are built.

For Estate Planning Professionals

Consider adding the AMD as a standard module in every comprehensive estate plan above a defined threshold. The document is not complex to produce. What requires expertise is the legal drafting, the registration process, and the coordination with the client’s medical team and Nominated Representative. This is a service gap that trained legal and advisory teams can fill — and that clients will remember.

The Process: How to Execute an Advance Medical Directive in India

Executing a valid AMD in India currently involves the following steps, consistent with MHA 2017 and the Supreme Court’s simplified 2023 guidelines:

  • Legal Drafting: Retain a qualified advocate — ideally with experience in medico-legal matters and an understanding of the relevant clinical terminology — to draft the AMD in accordance with MHA 2017 and the Supreme Court guidelines.
  • Medical Consultation: Discuss the document with your primary physician or a palliative care specialist. Ensure that the clinical conditions and treatment decisions described in the AMD are medically coherent and reflect an informed understanding of the relevant conditions.
  • Execution and Witnessing: Sign the AMD in the presence of two independent witnesses who are not the Nominated Representative, are not related to the maker by blood or marriage, and have no financial stake in the outcome.
  • Countersignature of a Gazetted Officer or Notary: As per the Supreme Court’s 2023 simplification, a notary or gazetted officer may now countersign the document. The original JMFC procedure also remains available and may be preferred in some jurisdictions for additional legal certainty.
  • Custody and Distribution: Retain the original, provide a certified copy to the Nominated Representative, provide a copy to the primary physician, and if possible, register a copy with the local medical authority or a national registry. Ensure the document is accessible in a medical emergency.
  • Periodic Review: The AMD is not a static document. Review it every three to five years, or following any significant change in health status, family circumstances, or personal values.

The Conversation India’s Wealthy Families Need to Have

India is entering a period of unprecedented intergenerational wealth transfer. Over the next two decades, an estimated $8 trillion in assets is expected to pass from the founding generation to the next. The planning infrastructure for this transfer is rapidly professionalising: family offices are multiplying, succession laws are being studied, philanthropic vehicles are being structured.

But no amount of financial sophistication insulates a family from the moment when the patriarch or matriarch lies in an ICU, unable to speak, with the family frozen in anguish and the medical team acting on the default of maximum intervention.

The Living Will — the Advance Medical Directive — is the document that inserts the person back into that moment. It is the final act of autonomy. It says: I have thought about this. I have decided. This is my voice, even when I have no voice.

For India’s wealth planning industry, the Living Will is not a peripheral concern. It is the missing document in every comprehensive wealth plan. The families who execute it thoughtfully will face that ICU moment — if it comes — with legal clarity, financial protection, and the profound comfort of knowing that the person they love is being treated as they wished.

That is not a medical conversation. That is the most important wealth planning conversation you can have.

The Will protects your assets. The Living Will protects you.

About the Author

Prashant Ajmera is the Founder and Advocate at Ajmera Law International (ALI), a cross-border law firm established in 1993 and headquartered in Ahmedabad with a presence in Dubai. He holds a B.Sc., LL.M. (India), and ICSA (UK) and is a Canadian citizen. He is the author of ‘Millionaires On the Move’ (2019) and ‘How to Plan for Child’s Foreign Education’ (2020). His firm’s Advance Medical Directive practice serves HNI and UHNI families across India with medico-legal advisory, AMD drafting, registration coordination, and cross-border Living Will alignment. He is also the founder of the Lawyers for Organ Donation Law (LODL) network and co-founder of OneIndiaOneLaw.org.

Contact: prashant@ajmeralaw.com  |  +91 98986 98184  |  www.ajmeralaw.com


This article is for general information and public awareness purposes only and does not constitute legal or medical advice. Readers should consult qualified legal counsel and medical professionals before executing an Advance Medical Directive.

June 15, 2026

Don’t Put All Your Eggs in One Bazaar:  Why Every Indian Investor Must Think Beyond Dalal Street

By Prashant Ajmera, AjmeraCapital.com  |  March 2026  |  8 min read

Imagine investing your life savings entirely in one city’s real estate — say, only in Ahmedabad — while ignoring Mumbai, Bangalore, and every other booming market. Sounds risky? Yet, that is precisely what millions of Indian investors do every year when they restrict their portfolios to domestic stocks and mutual funds alone.

India’s economy is a powerhouse, no doubt. But the world’s financial markets are a universe far larger than even our most optimistic projections. For the savvy Indian investor, going global is no longer a luxury — it is a necessity.


~3%

India’s Share of World GDP

190+

Countries to Invest In

60%+

Nifty 50’s 10-yr Return

$25T+

US Market Cap Alone


The Illusion of the ‘Safe’ Home Market

It is a deeply human instinct to invest in what we know. Indian investors are intimately familiar with TCS, Infosys, Reliance, and HDFC Bank. There is comfort in reading local news, understanding regulatory trends, and tracking companies whose products we use every day. This is called home bias — and it is one of the most expensive investing mistakes one can make.

Here is the hard truth: despite India’s impressive GDP growth story, the Indian stock market represents only about 3% of the global equity market capitalisation. By staying home, you are voluntarily ignoring 97% of the world’s investment opportunities.

“Diversification is the only free lunch in investing.” — Harry Markowitz, Nobel Laureate in Economics

Why Global Diversification Makes Sense for Indians

  1. Currency Advantage

The Indian Rupee has historically depreciated against the US Dollar at roughly 3–5% per year. When you invest in dollar-denominated assets, you gain not just market returns but also the currency appreciation benefit. A 10% return in US stocks can effectively become 13–15% in rupee terms.

  1. Access to World-Class Sectors

India’s stock market, while vibrant, has limited exposure to certain high-growth global sectors. Want to invest in semiconductor giants like NVIDIA, electric vehicle leaders like Tesla, or AI infrastructure companies? These opportunities simply do not exist on Indian exchanges at scale.

  1. Economic Cycle Decoupling

Indian and global markets don’t always move together. When Indian markets correct due to domestic factors — monsoon failures, political uncertainty, or RBI policy shifts — US, European, or Asian markets may continue to grow. This non-correlation is the very heart of risk reduction.

  1. Inflation-Beating Growth

With retail inflation remaining sticky in India, preserving purchasing power is critical. Global equities — particularly US technology and healthcare — have historically delivered real returns that comfortably beat domestic inflation over long time horizons.

  1. Your Future Expenses Are Already in Foreign Currency — Plan Accordingly

Here is a statistic that should make every Indian High Net Worth Individual (HNI) sit up and take notice: Indian residents remit over USD 31 billion every year out of the country — for children’s overseas education, international travel, medical treatment abroad, and foreign currency purchases at prevailing market rates.

This is a massive, recurring outflow — and most families fund it by converting rupees to dollars or pounds at the current exchange rate, bearing the full brunt of rupee depreciation at the time of need. The smarter alternative? Let your foreign investments do the heavy lifting.

When you build a portfolio of international assets over 10–15 years, you are essentially creating a foreign currency fund earmarked for exactly these life goals. The investment returns — in dollars, euros, or pounds — can directly pay for your child’s tuition at a UK or US university, cover your family’s annual international travel, or fund a medical procedure abroad, without you ever needing to scramble for foreign exchange at an unfavourable rate.

Think of it this way: if you invest USD 500 per month in a US index fund starting when your child is 5 years old, by the time they turn 18 and are ready for university, you could have a substantial dollar-denominated corpus — funded by market growth, not just savings — ready to deploy. No last-minute currency conversions. No anxiety about the rupee’s rate on the day you need to pay fees. Just financial readiness.

Indian HNIs remit over $31 billion abroad every year. Foreign investments don’t just grow your wealth — they pre-fund your biggest future dollar expenses at today’s prices.

Where Should Indian Investors Look?

Not all global markets are created equal. Here is a strategic breakdown:

  • United States: The world’s largest equity market, home to tech titans, pharmaceutical innovators, and consumer giants. Ideal for long-term, growth-oriented portfolios.
  • Europe: Offers exposure to luxury goods, banking, energy, and industrials — sectors underrepresented in India. Generally more value-oriented.
  • China & Southeast Asia: High-risk, high-reward. Suitable for investors with a higher risk appetite and long time horizons.
  • Gold & Commodities (International ETFs): A classic hedge against both rupee depreciation and market volatility.
  • REITs (International Real Estate): Countries like Singapore and the US have mature REIT markets offering stable dividend income.

How to Get Started: Practical Steps for Indian Investors

The good news is that it has never been easier for Indians to invest globally. Here are the primary routes:

Mutual Funds with International Exposure

Several Indian fund houses — PPFAS, Motilal Oswal, Mirae Asset — offer funds that invest in global stocks. These are SEBI-regulated, tax-efficient, and require no foreign account. This is the easiest starting point.

Liberalised Remittance Scheme (LRS)

Under RBI’s LRS, every Indian resident can remit up to USD 2,50,000 per financial year to invest directly in foreign stocks and ETFs through platforms like Vested, INDmoney, or Stockal.

International ETFs on NSE/BSE

Several international index ETFs trade directly on Indian exchanges in rupees — including those tracking Nasdaq-100, S&P 500, and global commodity indices.

The Tax Reality: What You Must Know

Global investing comes with tax implications that Indian investors must understand before taking the plunge:

  • Gains from international mutual funds held for less than 24 months are taxed as short-term capital gains (STCG) at your income tax slab rate.
  • Long-term capital gains (beyond 24 months) from international funds are taxed at 12.5% without indexation.
  • Direct foreign stock investments under LRS may attract TCS (Tax Collected at Source) at 20% on remittances above ₹7 lakh — though this is adjustable against your final tax liability.
  • India has Double Taxation Avoidance Agreements (DTAA) with many countries, which can reduce your overall tax burden.

Always consult a qualified tax advisor before making significant cross-border investments.


A well-diversified Indian investor should ideally have 15–25% of their equity portfolio in international assets. Even a modest 10% allocation can meaningfully reduce overall portfolio volatility.

Common Myths — Busted

Myth 1: ‘Global investing is only for the ultra-rich.’

Reality: International mutual funds allow SIPs starting at ₹500. You don’t need USD 10,000 to go global.

Myth 2: ‘US markets are overvalued and about to crash.’

Reality: Timing any market is impossible. Consistent SIP investments in international funds smooth out valuation risks over time, just as they do in domestic SIPs.

Myth 3: ‘I don’t understand foreign companies.’

Reality: Index funds require no stock-picking. Buying a Nasdaq-100 ETF means you own Apple, Microsoft, and Alphabet — companies whose products you likely use every day.


The Bottom Line

India’s growth story is real and compelling. The Sensex has given extraordinary returns over decades, and domestic opportunities remain abundant. But betting everything on one country — even your own — is a gamble no serious investor should take.

Global diversification is not about distrust in India. It is about financial wisdom. It is about ensuring that your wealth can grow regardless of what any single market, currency, or economy does.

The world’s biggest fortunes are built by investors who think globally, allocate wisely, and let compounding do its work — across borders.

Start small. Start today. Because when it comes to your financial future, the whole world is your market.

Next month I will write about three different Real Estate Investment Opportunities in USA with very low investment

Disclaimer: This article is for educational purposes only and does not constitute financial advice. Please consult a SEBI-registered investment advisor before making investment decisions.

 By: Prashant Ajmera, | Founder: AjmeraCapital.com | Mo: +919974253030 | Email: info@ajmeracapital.com

May 24, 2026

Portugal Is Not on Most Indian Business Leaders’ Radar. It Should Be.

By Prashant Ajmera  |  Founder, Ajmera Law International

Global Mobility & Cross-Border Law  |  30+ Years  |  20+ Countries


Here is a question I ask every Indian entrepreneur who walks into my office talking about Europe:

“Which country do you want to enter first?”

The answer is almost always the same. UK. Germany. Netherlands. Sometimes France.

Portugal almost never comes up.

And that is precisely why I am writing this article.

What Is Already Happening in Portugal — That Most People Do Not Know

Let me share something that surprises most Indian business leaders when I tell them.


Company Location What They Do
HCLTech Lisbon Digital Shared Services Centre since 2009. Product support, data analytics, EU-compliant delivery.
TCS Lisbon Delivery centre for European banking and financial services clients.
Infosys Lisbon Registered branch — Infosys Limited Sucursal em Portugal.
Wipro / Appirio Porto Commerce Cloud Centre of Excellence & Innovation Hub. Hiring local Portuguese talent.
Aurobindo Pharma Nationwide Acquired Generis — one of the most significant Indian pharma entries into the EU via Portugal.
Mahindra Portugal Active in automotive and technology sectors.
MGM Group Lisbon / Algarve Hospitality sector operations.
Sugee Group Portugal Real estate development.
Flying Wedge Defence Portugal 2025: Manufacturing AI autonomous aircraft Kaal Bhairava — first overseas production facility.

In total, Indian investments in Portugal are estimated at US$450 million. Approximately 180,000 persons of Indian origin live in Portugal today — a ready-made community, a ready-made network, and a ready-made market.

India’s biggest IT firms figured this out fifteen years ago. The question is: why haven’t more Indian SMEs, founders, and investors?

Then Came January 27, 2026 — Everything Changed

On January 27, 2026, at Hyderabad House in New Delhi, the European Union and India concluded negotiations on what is now being called — by both sides — the mother of all trade deals.

The India-EU Free Trade Agreement. Nearly two decades in the making. Finally done.

What It Means in Numbers

Consumers Covered 2 Billion — India + EU combined
Share of Global GDP 25% in one trade partnership
Indian Exports at Zero Duty 91% from Day One of entry into force
EU Goods Tariff Elimination 96.6% over 7 years
EU Service Subsectors Opened 144 — including IT, finance, professional services
FTA Concluded January 27, 2026 — Hyderabad House, New Delhi
Expected Entry into Force Early 2027 (after EU Parliament ratification)
Professional Mobility Formal framework for ICTs, business visitors, independent professionals


“This agreement creates the world’s largest free trade zone — two billion people, one quarter of global GDP, and a partnership built for the next century.” — European Commission President Ursula von der Leyen, January 2026

And critically for Indian businesses considering Europe: Portugal ratifies as part of the EU. One deal. One market. Portugal is your door in.

The window to enter, structure, and establish yourself before that moment — is right now

Why Portugal Specifically — Not Germany, Not France, Not the UK

I want to be direct here, because I see too many Indian businesses make this mistake. They choose their European entry market emotionally — based on familiarity, language, or where they attended a conference.

Portugal deserves a strategic conversation. Here is why.

  1. The Global Language Bridge

Portugal is a gateway not just to Europe’s 450 million consumers, but to Portuguese-speaking markets — Brazil, Mozambique, Angola, Cape Verde. If your business has any interest in lusophone markets, Portugal is an extraordinary launchpad.

  1. Highly Competitive Cost Base Within Western Europe

Operational costs — office space, talent, local management — are substantially lower than Germany, France, or the Netherlands. For Indian SMEs building their first European operation, this matters enormously.

  1. A Genuinely Startup-Friendly Regulatory Environment

Portugal introduced a dedicated Startup Visa — one of the most accessible founder immigration routes in the EU. The India-Portugal Startup Hub, created under a formal MoU between Startup Portugal and Invest India, is an active institutional bridge between both ecosystems.

  1. 180,000 Strong Indian Community

This is not just a diaspora statistic. It is a business network, a talent pipeline, a cultural bridge, and a customer base. Indian founders entering Portugal are not entering cold — they are entering a country where Indian business is already trusted and established.

  1. Direct Diplomatic Momentum at the Highest Level
  • India’s President Droupadi Murmu visited Portugal in April 2025 — the first Indian state visit in 27 years.
  • Finance Minister Nirmala Sitharaman met her Portuguese counterpart in Lisbon, July 2025.
  • Portugal’s Secretary of State for Economy is actively building a regulatory bridge for Indian and Portuguese companies.
  • India and Portugal held their 1st bilateral consular dialogue in November 2024.

This is not background noise. This is signal.

What Indian Companies Are Getting Right — And What They Are Getting Wrong

What the Successful Ones Get Right

HCLTech did not just open an office in Lisbon. They set up a Digital Shared Services Centre with a proper local entity, employment structure compliant with Portuguese labour law, and service delivery frameworks aligned with EU data protection rules.

Aurobindo did not just export medicine to Portugal. They acquired Generis — a locally regulated, properly licensed pharmaceutical company — giving them instant compliance infrastructure and market credibility.

These are not accidents. These are the results of deliberate legal and structural planning before market entry.

What the Unsuccessful Ones Get Wrong

The Indian companies that have stumbled in European markets almost always made the same errors:

  • Entered informally, operating before the entity was properly incorporated
  • Assumed their Indian contracts, IP registrations, and employment frameworks would travel with them — they do not
  • Did not register their trademarks in Portugal before launch — and found competitors had done it for them
  • Ignored Portuguese labour law — which is employee-protective and very different from Indian norms
  • Had no GDPR compliance structure — which in the EU is not optional, it is existential

Portugal is welcoming. The legal framework is accessible. But it still requires proper entry architecture.

The Practical Checklist: Before You Enter Portugal

Whether you are a founder considering your first EU entity, an SME exploring a distribution partnership, or an investor looking at the Golden Visa route — these are the non-negotiables before you take a single step:

  • Choose Your Entity Structure Deliberately — Lda (Private Limited) vs SA (Public Limited)? Branch vs subsidiary? Each has different tax, liability, and banking implications for your Indian parent company.
  • Understand Your Founder and Team Mobility Pathway — Startup Visa? Intra-company transfer? The India-EU FTA now includes a formal mobility framework — the right route depends on your company structure, your role, and your business model.
  • Register Your IP in Portugal Before You Launch — Trademark registration in Portugal is an EU trademark through EUIPO — covering all 27 member states. Do this before your first commercial activity. Not after.
  • Structure Your India-Portugal Tax Position Correctly — India and Portugal have a Double Taxation Avoidance Agreement. Transfer pricing between your Indian entity and Portuguese subsidiary must be documented from day one.
  • Build GDPR Compliance Into Your Operations From the Start — If you handle any data from EU residents — customers, employees, partners — you are subject to GDPR. This includes website analytics, CRM, and email marketing.
  • Know Your Banking Pathway — Indian-owned EU companies can open Portuguese bank accounts — but the KYC process requires proper documentation of your India-Portugal corporate structure. Plan this in advance.

A Personal Note — Why This Moment Matters

I founded Ajmera Law International in 1993. For over thirty years, I have watched the arc of Indian business ambition.

In the 1990s, going global meant IT services outsourcing. In the 2000s, it meant pharma exports. In the 2010s, it meant startup ecosystems and unicorn valuations.

In 2026, something different is happening. It is quieter. More deliberate. More serious.

Indian founders are not just looking to serve European clients from India anymore. They want to be present in Europe. To build European businesses. To access European capital, European talent, and European markets from the inside.

The India-EU FTA — the largest trade agreement either side has ever concluded — is the formal acknowledgement by two of the world’s largest economies that this is the right moment.

Portugal, with its Indian community, its startup ecosystem, its lower cost base, its language bridges to lusophone markets, and its established Indian corporate presence from HCL to Aurobindo — is arguably the most strategically underrated entry point into the EU for Indian businesses today.

The companies that recognise this now, structure properly, and build patiently — will have a meaningful advantage over those who arrive two years from now when the FTA is in force and the market is crowded.

Watch this EU webinar series playlist – https://www.youtube.com/watch?v=Iz3JN8rJJGU&list=PLta9RijQ5wdRN_eXYBlIwVAmTWfCMjsUs

Or reach out to us directly:


📞 +91 99 74 25 3030 📧 info@ajmeralaw.com 🌐 www.ajmeralaw.com

About the Author

Prashant Ajmera is the Founder of Ajmera Law International (ALI), an Ahmedabad-based law firm with over 30 years of experience in business immigration, global mobility, and residency and citizenship by investment programmes across 20+ countries. ALI advises Indian businesses, HNIs, and families on structured, compliant, and strategic international expansion.

#IndiaToEurope  #Portugal  #GlobalExpansion  #IndiaEUFTA  #BusinessImmigration  #GlobalMobility  #AjmeraLawInternational  #CrossBorderLaw  #IndianBusiness  #EuropeanMarkets  #StartupPortugal  #GoldenVisa  #IndiaPortugal  #DealflowEU  #VenturesEU  #IndiaGoesGlobal  #FoundersOfIndia  #SMEIndia  #EUMarket  #IndiaEU


April 11, 2026

Here is your complete, website-ready blog post — clean, formatted, and ready to copy and paste directly into WordPress or any website CMS:


The EU-India Free Trade Agreement: A Game-Changer for Indian Business, Exports and Your Family’s Future in Europe

By Advocate Prashant Ajmera | Ajmera Law International | January 2026

How the world’s largest FTA — signed 27 January 2026 — reshapes Indian trade, and why the EU Golden Visa is the smart next step for every Indian exporter and entrepreneur.

On 27 January 2026, history was made at Hyderabad House in New Delhi. After nearly two decades of on-and-off negotiations, India and the European Union concluded the world’s largest free trade agreement — a deal covering 2 billion people and 25% of global GDP. For Indian businesses and exporters, the opportunity is not just significant. It is generational.

What Is the EU-India FTA — and Why Does It Matter?

The India-European Union Free Trade Agreement, concluded on 27 January 2026 at the 16th India-EU Summit in New Delhi, is the largest and most comprehensive trade deal either side has ever signed. It was announced jointly by Prime Minister Narendra Modi, European Commission President Ursula von der Leyen, and European Council President António Costa — who described it, without exception, as “the mother of all deals.”

The numbers tell the story. EU bilateral trade in goods with India already stands at €120 billion per year, with services adding a further €60 billion. The FTA is expected to double EU goods exports to India by 2032 — and in the reverse direction, it opens the EU’s 450-million-person market to Indian exporters at dramatically lower or zero tariffs for the first time.

The timing is also geopolitically significant. The deal came amid US tariffs of 50% on Indian goods and growing tensions between Washington and both New Delhi and Brussels. The EU-India FTA sends a clear message to the world: India has alternatives, strategic partners, and the economic scale to write its own trade story.

Key Features of the EU-India FTA

Here are the headline provisions that every Indian businessperson and exporter needs to understand:

96.6% of EU Goods — Tariffs Eliminated or Reduced

Tariffs on 96.6% of all EU goods exported to India will be eliminated or significantly reduced. This provides Indian manufacturers and consumers access to European machinery, chemicals, pharmaceuticals, and technology at far lower costs — reducing input prices and boosting industrial competitiveness.

India’s Labour-Intensive Exports — Zero Duty, Immediately

Indian exporters in textiles, apparel, leather, footwear, gems and jewellery, marine products, sports goods, and toys receive immediate zero-duty access to the EU market — without phased reduction. This represents a combined export opportunity worth INR 2.87 lakh crore across these sectors.

EU Car Tariffs: 110% → 10% Over Five Years

India agreed to slash car import tariffs from as much as 110% to 10% over five years, with quota-based annual access for 250,000 EU vehicles. In exchange, Indian auto component and EV manufacturers gain EU market access at preferential rates.

Pharmaceuticals and Medical Devices — 99%+ Eliminated

India’s world-class pharmaceutical sector gains access to the EU with tariffs up to 11% eliminated. For medical instruments and devices, tariffs of up to 6.7% are eliminated across 99.1% of trade lines — a quantum leap for Indian medtech exporters.

Agriculture and Processed Food — Preferential EU Access

Tea, coffee, spices, grapes, gherkins, dried onion, fresh vegetables, seafood (shrimp, frozen fish), and value-added foods all receive preferential tariff treatment in the EU — strengthening farmers’ incomes and rural livelihoods across India.

Digital Trade, IP and Services — A New Modern Framework

The FTA includes dedicated chapters on digital trade, intellectual property, investment protection, dispute settlement, and sustainable development. For Indian IT and professional services firms, expanded mobility provisions create new pathways for skilled professionals into EU markets.

Security, Defence and Mobility Partnership

Alongside the FTA, India and the EU signed a Security and Defence Partnership and a Mobility and Migration Agreement — substantially enhancing legal pathways for Indian students, skilled workers, and business professionals into the EU.

Sector-by-Sector: What Changes for Indian Exporters

Sector Current Tariff Post-FTA Tariff Benefit for India
Textiles & Apparel 12% 0% (immediate) Zero duty EU access — huge advantage
Leather & Footwear Up to 17% 0% (immediate) Price competitive vs China, Vietnam
Gems & Jewellery Up to 15% 0% (immediate) INR 2.87 lakh crore exports boosted
Marine / Seafood Up to 20% Reduced/0% Shrimp, fish — coastal state windfall
Pharmaceuticals Up to 11% Eliminated 99.1% of trade lines — zero duty
Medical Instruments Up to 6.7% Eliminated Medtech exports to EU — quantum leap
IT & Digital Services Various Enhanced access Mobility provisions for professionals
Agri / Processed Food Various Preferential Tea, coffee, spices — higher EU value
Home Décor & Furniture Up to 10.5% Reduced Bamboo, wooden crafts — new demand

Why Indian Businesses Must Act Now

The FTA is currently undergoing legal vetting and translation, expected to take five to six months. Formal signature and ratification by the EU Parliament and India’s Union Council of Ministers will follow — with implementation estimated within 12 months. This is your preparation window.

First Mover Advantage is Real. Indian businesses that proactively register as approved exporters, structure their supply chains to meet EU Rules of Origin requirements, and establish distribution networks in EU markets before the agreement enters force will gain a significant competitive lead over slower movers. The window to prepare is now — not after implementation.

Three types of Indian businesses stand to gain the most:

  • Exporters in textiles, apparel, leather, footwear, gems and jewellery, marine, and agri-food — who gain immediate zero or near-zero duty access to 450 million EU consumers.
  • Manufacturers and industrialists who will now access European machinery, chemicals, and technology inputs at dramatically lower cost — reducing their own production costs.
  • IT, digital, and professional services firms — who benefit from enhanced mobility provisions, IP protections, and new bilateral frameworks for digital trade.

The EU Golden Visa: The Smart Next Step for Every Indian Exporter

The EU-India FTA opens Europe’s market to your products. The EU Golden Visa opens Europe’s doors to you and your family. For any Indian entrepreneur or exporter doing — or planning to do — significant business in Europe, securing EU residency is no longer just a lifestyle aspiration. It is a strategic business decision.

An EU Golden Visa holder can live, work, do business, and travel freely across 29 Schengen countries. For an Indian exporter with EU clients, partners, and employees, having a legal EU base is not a luxury. It is a competitive advantage.

What Is the EU Golden Visa?

An EU Golden Visa — technically called a Residency by Investment programme — grants the investor, their spouse, children, and in many countries their parents, the legal right to live, work, study and access healthcare in a European Union member state. In exchange for a qualifying investment in real estate, investment funds, business, or cultural heritage, the investor receives a renewable EU residence permit.

The key features that make it compelling for Indian businesspeople:

  • No employer sponsorship, job offer, or professional qualification required
  • Family included in a single application — spouse, children, and in most countries parents
  • Visa-free travel across all 29 Schengen Area countries — including Germany, France, Italy, Netherlands, Spain, and more
  • Pathway to EU permanent residency and citizenship after five to ten years depending on country
  • No requirement to live in the country continuously — most programmes have minimal or zero minimum stay requirements
  • Investment can generate rental income or financial returns — it is not lost capital

Top EU Golden Visa Countries for Indian Investors in 2026

🇵🇹 Portugal — Best Route to EU Citizenship

  • Minimum Investment: €500,000 (investment fund)
  • Processing Time: Up to 18 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: EU Passport after just 5 years

🇬🇷 Greece — Most Affordable · Rental Income

  • Minimum Investment: €250,000 – €800,000 (real estate)
  • Processing Time: 2–4 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: After 7 years

🇮🇹 Italy — Business and Lifestyle Hub

  • Minimum Investment: €250,000+ (investment fund)
  • Processing Time: 3–4 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: After 10 years

🇲🇹 Malta — Immediate Permanent Status

  • Minimum Investment: €300,000+ (real estate/bonds)
  • Processing Time: 4–6 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: Permanent residency granted immediately

🇭🇺 Hungary — 10-Year Permit, Fastest Process

  • Minimum Investment: €250,000 (real estate fund)
  • Processing Time: 1–3 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: After 5 years full-time residence

🇱🇻 Latvia — Most Affordable EU Entry Point

  • Minimum Investment: €50,000+ (company/bonds)
  • Processing Time: 2–3 months
  • Schengen Access: All 29 Schengen countries
  • Path to Citizenship: After 10 years legal residence

EU Golden Visa Comparison for Indian Investors

Country Min. Investment Schengen Min. Stay Citizenship Best For
🇵🇹 Portugal €500K (fund) ✓ Yes 7 days/yr 5 years EU passport fastest
🇬🇷 Greece €250K–€800K ✓ Yes None 7 years Most affordable + rental income
🇮🇹 Italy €250K+ ✓ Yes None 10 years Lifestyle + business hub
🇲🇹 Malta €300K+ ✓ Yes None Permanent Immediate permanent status
🇭🇺 Hungary €250K (fund) ✓ Yes None After 5 yrs 10-yr permit, fast process
🇱🇻 Latvia €50K+ ✓ Yes None 10 years Most affordable entry point

EU Golden Visa: Business Benefits for Indian Exporters

For an Indian exporter or entrepreneur with EU trade interests, EU residency is a powerful business tool — not just a personal lifestyle upgrade.

EU Business Base — No More Visa Delays As an EU resident, you can open bank accounts, register companies, sign contracts, attend trade fairs, meet clients, and run operations in any of the 27 EU member states without visa applications, rejection risk, or travel restrictions. For exporters scaling up EU operations post-FTA, this freedom is invaluable.

Schengen Visa-Free Access — 29 Countries Indian passport holders currently need to apply for Schengen visas for every EU trip. An EU residence permit eliminates this friction entirely — you and your family travel across Europe as freely as EU nationals. Germany, France, Netherlands, Italy, Spain, Portugal: all accessible without a single visa application.

Attend Trade Fairs and Buyer Meetings Freely Europe hosts the world’s most important trade fairs — Hannover Messe, Frankfurt Book Fair, Paris Air Show, MEDICA, Ambiente, and hundreds more. EU residency means you are always ready to attend at short notice — no visa delays, no rejections, no missed opportunities.

EU Banking, Credit and Financial Services EU residents access EU banking, credit facilities, investment accounts, and payment infrastructure on local terms. For exporters receiving EUR payments, managing EU subsidiaries, or securing EU-based financing for expansion, an EU address is a practical necessity.

Tax Optimisation Opportunities Several EU Golden Visa countries offer attractive tax regimes for non-habitual residents (Portugal), retirees (Greece), and new residents (Italy’s flat tax scheme). For high-net-worth Indian families with global income, structured EU residency can offer meaningful tax planning opportunities — subject to professional advice.


EU Golden Visa: Family Benefits That Last Generations

The EU Golden Visa is not just a business tool — it is a multi-generational investment in your family’s future.

World-Class European Education for Your Children EU residents access some of the world’s finest universities at domestic or EU-rate tuition fees rather than prohibitive international student rates. Countries like Germany, Netherlands, and France offer outstanding higher education at a fraction of the cost of US or UK institutions. Your children study in Europe as EU residents, not international students.

Public Healthcare — European Standard EU residents access public healthcare systems in their country of residence — systems consistently ranked among the world’s best. This is particularly significant for aging parents who can be included in the Golden Visa application in most countries, securing their access to world-class medical care.

Entire Family — One Application A single Golden Visa application covers the investor, spouse, dependent children under 21, and in Portugal, Greece, Italy, and Malta, the parents of both the investor and spouse. Your parents can secure EU residency alongside you.

Second Home Base — Safety and Security An EU residence permit gives your family a legally secure second base in one of the world’s most stable, rule-of-law governed regions. In an increasingly uncertain global environment, this is meaningful insurance for your family’s future — independent of political or economic developments in any single country.

Path to EU Citizenship and Passport After five to ten years depending on country, Golden Visa holders can apply for EU citizenship — one of the world’s most powerful passports, offering visa-free travel to over 180 countries. Portugal offers this pathway in just five years, with minimal physical presence required.

The FTA + Golden Visa: A Combined Strategy

The EU-India FTA and the EU Golden Visa are most powerful when pursued together as a single, integrated strategy for Indian entrepreneurs and exporters.

The FTA gives your products privileged access to 450 million European consumers. The Golden Visa gives you the legal right to be there in person — to build relationships, manage operations, attend trade fairs, and establish your brand. Together, they represent the most powerful package available to any Indian entrepreneur in 2026.

Think of it this way:

  • FTA = Your products enter Europe at zero or minimal duty, price-competitive with local and rival-country suppliers
  • Golden Visa = You enter Europe freely, work legally, meet buyers without visa stress, and build a physical business presence
  • Together = A platform for sustained, scalable European market growth — anchored by legal residency, business access, and family security

Your Action Plan: Five Steps to Take Today

The implementation window for the FTA is approximately 12 months. Golden Visa processing takes two to 18 months depending on the country. There is no better time to begin both journeys than now.

Step 1 — Review your export sectors Identify which of your products attract EU tariffs today. Most labour-intensive goods now enjoy zero or near-zero duty access under the FTA.

Step 2 — Register as an EU-approved exporter Understand Rules of Origin (RoO) requirements. Your products must meet minimum value-addition thresholds to qualify for FTA preferences.

Step 3 — Explore EU market entry partners Leverage the EU’s 6,000 existing India-linked companies. Seek distribution, JV or agency agreements with EU counterparts in your sector.

Step 4 — Consult on EU Golden Visa suitability Assess which EU country’s Golden Visa best fits your business plans, family needs and investment capacity. Portugal, Greece, Italy and Hungary are top picks for Indian investors.

Step 5 — Engage Ajmera Law International All legal, immigration and investment structuring — across both the FTA compliance and the Golden Visa application — can be handled through a single expert partner.

Why Ajmera Law International?

Navigating the EU-India FTA compliance requirements, market entry structuring, and a Golden Visa application simultaneously requires expertise across international trade law, EU immigration law, and investment advisory — in two jurisdictions. Ajmera Law International brings all of this under one roof.

Our clients benefit from single-point accountability: one firm, one team, one relationship — managing the legal, compliance, and advisory dimensions of your entire EU strategy. Whether you are an MSME exporter taking your first steps into European markets, or an HNI family seeking EU residency and citizenship, we have the expertise and the network to guide you.


📞 +91 99 74 25 3030 ✉ info@ajmeralaw.com 🌐 www.ajmeralaw.com


Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or immigration advice. The EU-India FTA has concluded negotiations as of 27 January 2026 and is subject to legal vetting, ratification, and implementation procedures before entering into force. EU Golden Visa programme terms, investment thresholds, and eligibility criteria are subject to change. All information is based on publicly available sources as at the date of publication. Please consult a qualified legal advisor for advice tailored to your specific circumstances. Ajmera Law International is a legal advisory firm — contact us directly for personalised guidance.
March 22, 2026

Why Indian Investors Are Turning to USA Real Estate in 2026?

A complete guide to the three pathways — USD returns, INR returns, and the EB-5 Green Card — and why now may be the right time to act.

For decades, Indian investors have trusted gold, FDs, and domestic property to build and protect wealth. But in 2026, a growing number of high-net-worth individuals, NRIs, and forward-thinking families are looking westward — to the United States real estate market — for diversification, superior returns, and a life-changing legal pathway to permanent US residency.  –


The Case for USA Real Estate — Why Now?

The US real estate market has historically delivered consistent long-term growth, outperforming many other global asset classes. For Indian investors, it represents an opportunity to hold a hard asset in one of the world’s most stable economies — backed by the rule of law, transparent title systems, and a currency that acts as the world’s reserve.

At the same time, India’s increasing global integration has made cross-border investing more accessible than ever. With the RBI’s Liberalised Remittance Scheme (LRS) allowing up to USD 250,000 per individual per year, and structured legal pathways available through firms like Ajmera Law International, the barriers to entry have never been lower.

Whether your goal is portfolio diversification, building a USD corpus for a child studying abroad, or securing US permanent residency — there is now a structured, legal, and professionally guided path to each of these outcomes through a single trusted partner in the USA.

Three Reasons Indian Investors Are Choosing USA Real Estate

1. Portfolio Diversification
India’s domestic markets — equities, property, and fixed income — are subject to local monetary policy, inflation cycles, and currency fluctuation. Holding a portion of wealth in USD-denominated US real estate acts as a natural hedge. When the rupee weakens, your dollar-denominated asset appreciates in INR terms automatically.

2. Children’s Education Planning
The cost of a US undergraduate or postgraduate education runs between USD 40,000 and USD 80,000 per year at reputed institutions. Investing today in a US real estate structure that generates dollar returns is one of the most practical ways to build an education corpus in the currency you will actually spend — eliminating forex uncertainty at the time of payment.

3. USA Green Card via EB-5
The EB-5 Immigrant Investor Program is the US government’s official pathway to permanent residency through investment. It is the only visa category in the USA that does not require a job offer, employer sponsorship, or extraordinary talent — just a qualifying investment in a USCIS-approved project.


The Three Investment Pathways — Explained
Ajmera Law International offers Indian investors three distinct structures, each designed for a different investor profile, risk appetite, and goal.

OPTION 01
Invest in USD. Earn in USD.
This structure is designed for investors who want to build genuine dollar-denominated capital in the United States. Your investment goes into US real estate and your returns are received in USD — making it ideal for those planning future USD expenditures such as education fees, international travel, or eventual relocation.
Min. Investment: USD 50,000

✓ Full dollar exposure — both investment and returns in USD
✓ Natural hedge against INR depreciation over time
✓ Suitable for NRIs and resident Indians with USD income or LRS headroom
✓ Ideal for building a USD corpus for children’s education abroad

OPTION 02
Invest in INR. Earn in INR.
This pathway is specifically structured for Indian investors who prefer to stay within the rupee ecosystem — no forex conversion, no LRS complexity, no currency risk. You invest in Indian rupees and receive your returns in Indian rupees, while benefiting from underlying returns generated by US real estate.
Min. Investment: ₹ 25,00,000

✓ Invest and receive returns entirely in Indian Rupees
✓ No forex conversion required — zero currency complexity
✓ Potential for returns superior to domestic fixed income
✓ Ideal for HNIs and family offices seeking diversification without currency exposure


OPTION 03
Invest Your Way to a USA Green Card.
The EB-5 Immigrant Investor Program is administered by USCIS. A qualifying investment in an approved US project — typically in real estate development — places an investor on the path to a US Green Card for themselves and their immediate family members.
Min. Investment: USCIS Prescribed Amount

✓ US Green Card for investor, spouse, and unmarried children under 21
✓ Investment placed in a USCIS-approved, job-creating US project
✓ No employer sponsorship, job offer, or special skills required
✓ Full legal guidance from a qualified immigration law firm
✓ Access to world-class US education, healthcare, and lifestyle

Side-by-Side Comparison

Not sure which pathway suits you best? Here is a quick comparison across the three options to help you identify the right fit for your goals and investor profile.


Feature Option 1 — USD Option 2 — INR Option 3 — EB-5
Investment Currency USD INR USD (USCIS min.)
Returns Currency USD INR USD + Green Card
Minimum Entry USD 50,000 ₹ 25,00,000 USCIS Prescribed
Forex Risk USD Exposure ✓ None USD Exposure
Green Card Pathway ✗ No ✗ No ✓ Yes
Ideal For NRIs, USD earners HNIs, domestic investors Families seeking residency
Legal Complexity Low–Medium Low Medium (fully guided)


Why Ajmera Law International?
“Navigating cross-border investment requires more than a financial advisor — it requires legal expertise in two jurisdictions, an understanding of immigration law, and a trusted network on the ground in the USA.” — Ajmera Law International

Ajmera Law International is a law firm specialising in international legal and investment advisory services for Indian investors and NRIs. All three investment options are managed through a single, vetted US company — meaning you deal with one trusted partner for the entire journey, from initial consultation to return realisation or Green Card approval.

For investors unfamiliar with the US legal and regulatory environment, this single-point accountability is invaluable. There is no need to independently identify US real estate developers, navigate USCIS paperwork, or manage forex remittances without guidance. Ajmera Law International handles the legal, compliance, and advisory dimensions — so you can focus on the investment decision itself.

Is This Right for You?
USA real estate investment via these structured pathways is suited to a wide range of Indian investor profiles:
High-Net-Worth Individuals (HNIs) seeking to diversify beyond domestic equities and property into a globally respected, stable asset class will find the USD and INR options compelling.

Parents of children aged 5–16 who anticipate US university education costs in 10–15 years have a strong incentive to begin building a dollar-denominated corpus today.

NRIs currently living abroad — particularly in the Middle East, UK, or Southeast Asia — considering a long-term move to the United States will find the EB-5 pathway a professionally structured, legally robust route to US permanent residency.
Business families and entrepreneurs who wish to establish a physical or legal presence in the United States — for business expansion, family relocation, or asset protection — will benefit from Ajmera Law International’s holistic legal advisory. Download PDF File of the Blog

Meet Us at GATE Trade Show — Gandhinagar
The Ajmera Law International team will be present across all three days at the GGAT Trade Show in Gandhinagar. This is your opportunity to meet us in person, ask questions, and take the first step towards your USA investment journey — with no obligation.

★ MEET US IN PERSON ★
GATE Trade Show — Gandhinagar
16 • 17 • 18 April 2026 | Gandhinagar, Gujarat, India | Stall No: B93

Get in Touch: Ready to explore your options? Our team is available to answer your questions and guide you through the right pathway for your goals.

📞
Phone / WhatsApp
+91 99 74 25 3030 ✉️
Email
info@ajmeralaw.com 🌐
Website
www.ajmeralaw.com

Disclaimer: This document is for informational purposes only and does not constitute financial, legal, or investment advice. All investment decisions should be made after independent due diligence and consultation with a qualified legal and financial advisor. Returns on investments are subject to market conditions and are not guaranteed. The EB-5 visa programme is subject to USCIS regulations and approval timelines which may vary. Ajmera Law International is a legal advisory firm — please consult directly for advice tailored to your personal circumstances.

January 17, 2026

FIXING CANADA’S IMMIGRATION SYSTEM: A COMPREHENSIVE REFORM AGENDA

Canada’s immigration system faces an unprecedented crisis. With processing backlogs exceeding 2 million applications, record asylum claims, and public confidence eroding, urgent systemic reforms are essential. This document outlines concrete measures to restore integrity, efficiency, and public trust.

Implement Strict Application Caps Across All Programs

Canada must extend application intake caps—already used for family sponsorship—to all immigration classes. The federal government should set annual targets for Express Entry, Provincial Nominee Programs, and other streams, halting intake once quotas are reached. This prevents endless backlogs and ensures IRCC can process applications within reasonable timeframes. For 2025, IRCC already capped international study permits at 360,000, resulting in a 45 percent drop in approvals. Similar mechanisms should apply universally, not selectively.

Eliminate Job Offer Points from Economic Immigration

Job offers in Express Entry currently award up to 200 Comprehensive Ranking System points, fueling a black market for fraudulent Labour Market Impact Assessments (LMIAs). Large payments to sponsors for fake job offers have become systemic. In December 2024, Canada finally removed job offer points from Express Entry, refocusing on human capital: education, language proficiency, and work experience. This reform must extend to all economic pathways, ending payments for sponsorship letters and ensuring selection based on genuine skills, not documents purchased from intermediaries.

Restrict Work Permit Flexibility and Strengthen Employer Verification

Foreign workers on LMIA-based permits currently face enforcement gaps allowing unauthorized job switching. Impose strict no-switching rules for the first two years of employment and conduct rigorous audits of sponsoring companies to verify genuine labor needs and workplace standards. This protects Canadian workers while deterring exploitation of temporary resident schemes.

Block Low-Level Education Pathways to Immigration

Post-secondary college studies, particularly at unregulated community colleges, increasingly serve as backdoors to work permits and permanent residency via the Canadian Experience Class, drawing applicants with no genuine study intent. Canada should deny work permit or PR pathways for non-university diplomas, reserving such routes for bona fide bachelor’s and advanced degree holders. Recent study permit caps (capped at 360,000 for 2025) are a step forward but must be accompanied by credential verification and institution monitoring.

Reform Entrepreneur and Start-Up Programs

The Start-Up Visa program, which processed over 16,000 files involving 43,000 applicants, was suspended in December 2025 due to backlogs, unconditional permanent residence pathways, and fraudulent letters of support issued by fee-charging designated organizations. Future entrepreneur programs must abandon one-step permanent residency. Instead, require monitored temporary status first, granting PR only after proven business success within Canada. The pending 2026 Entrepreneur Pilot offers this opportunity.

Regulate Education Agents and Institutions Strictly

Immigration agents in source countries, particularly India and Philippines, systematically recruit low-quality students via forged documents and false job promises. In 2024, IRCC uncovered over 10,000 fraudulent letters supporting international student applications. Canada must impose strict monitoring of Canadian educational institutions and their foreign agent networks, with penalties for non-compliance. Mandatory agent licensing and victim compensation funds are essential to curb fraud and protect defrauded applicants.

Permanently Ban Visitor-to-Work Permit Conversions

Allowing visitor visa holders to apply for work permits from within Canada—a temporary policy in effect from 2020 to August 2024—enabled widespread status gaming. Permanently ban such conversions to preserve system integrity and prevent individuals from bypassing proper work permit channels.

Cap Asylum Seekers and Refugee Intake

Canada’s Refugee Protection Division faces a record backlog of 291,975 claims as of July 2025, with monthly surges adding thousands more. Canada must establish an annual asylum intake cap aligned with processing capacity and settlement resources. For 2025, the government reduced Government-Assisted Refugees to 16,000 and cut Privately Sponsored Refugee targets by 30 percent—steps in the right direction but insufficient without capping inland claims. Limit asylum applications to verified persecution cases and end mass resettlement from ongoing war zones. War-affected countries such as Sudan, Ukraine, Gaza, and Syria generate continuous displacement; accepting unlimited claimants from conflict zones strains housing, healthcare, and social services while enabling applicants to game the system through prolonged backlogs.

Update Asylum Law for the 21st Century

The 1951 Refugee Convention, drafted after World War II when refugee crises were discrete and geographically bounded, cannot accommodate 2026’s permanent global conflicts. Modern asylum law must distinguish between short-term emergency situations and indefinite conflicts, offering temporary protection for the former and strictly limiting permanent resettlement for the latter. Countries worldwide facing similar pressures have adopted tighter approaches; Canada must follow suit while maintaining humanitarian commitments to the most vulnerable.

Strengthen Humanitarian and Compassionate (H&C) Program Controls

The H&C program, designed for exceptional hardship cases, has become a de facto residency loophole. Processing times range from 12 to 600 months, with inventory reaching 49,900 applications. Rejected asylum seekers file H&C applications to secure work permits during prolonged backlogs, effectively converting refusals into indefinite stays. IRCC must implement strict intake caps for H&C, establish service standards with clear timelines, and differentiate between applicants (Canadian-born dependents vs. economic migrants reframed as humanitarian cases).

Monitor Educational Institutions and Agents

Education consultants and recruitment agents abroad promise international students employment and quick permanent residency, not education. These agents, working with Canadian institutions desperate for tuition revenue, supply poor-quality students who abandon studies for low-wage work. Canada should audit Canadian educational institutions and their foreign partnerships, audit approval of agents abroad, and tie international enrollment targets to institutional compliance with recruitment ethics.

Increase Enforcement and Deportations

Canada must accelerate deportations of rejected asylum seekers and individuals overstaying permits. Current processing backlogs and weak enforcement have created a de facto refuge for failed claimants and status violators. Dedicating IRCC resources to removals—not just processing applications—would reinforce system credibility and deter abuse. Those remaining in Canada despite refusals face no consequences, signaling that non-compliance is tolerated.

Align Immigration Levels with Housing and Service Capacity

Permanent immigration targets of 365,000 (2027) and earlier targets of 500,000 (2025) were set without regard to housing availability, healthcare capacity, or infrastructure. Massive temporary resident populations (6.5 percent of Canada’s population in 2024, targeted to shrink to 5 percent by 2026) overwhelmed housing markets. Future targets must be based on rigorous capacity assessments, including available housing units, hospital beds, school spaces, and language training seats. Public support for immigration depends on demonstrable integration success.

Boost IRCC Processing Capacity

Despite processing millions of applications annually, IRCC faces chronic understaffing and outdated systems. Wait times for spousal sponsorship exceed 23 months in non-Quebec Canada, and applications for humanitarian relief face 50-year backlogs. The federal government must significantly increase IRCC funding for hiring, training, and digital modernization. Service standards should be binding with automatic refunds or fast-tracking when exceeded.

Prevent Application Cancellations

Bills C-2 and C-12 propose granting IRCC unilateral authority to cancel applications without recourse. This would punish applicants for government mismanagement. Instead, if intake caps are exceeded, simply stop accepting new applications—do not retroactively cancel those already received. Cancellation powers would destroy Canada’s reputation for procedural fairness and predictability, precisely the qualities that historically made it an immigration leader.

Create Transparent Communication and Timelines

Applicants face uncertainty as processing times fluctuate weekly with no clear communication. IRCC should publish monthly updates on processing times by program, inventory levels, and expected decisions. Clear timelines—even if lengthy—are better than uncertainty. Where backlogs are severe, applicants should be informed upfront of realistic wait times or offered alternative pathways.

Conclusion

Canada’s immigration system, once a global model, has deteriorated into a backlog-ridden, fraud-prone apparatus that neither serves applicants nor advance Canada’s economic interests. Implementing strict intake caps, eliminating job offer fraud, capping asylum intake from conflict zones, reforming asylum law for modern realities, strengthening enforcement, and expanding IRCC capacity are essential first steps. These measures—rooted in integrity, efficiency, and realism—can restore public confidence and position Canada as a competent, fair immigration leader. The alternative is continued decline, public backlash, and a system so burdened that it serves no one.

The Author  Prashant Ajmera is an immigartion lawyer in India and also Canadian Citizen since 1997 and founder of Ajmera Law International – Global Mobility and Cross Border Law – www.ajmeralaw.com |Mo: +91 9898698184 | inof@ajmeralaw.com


1