💬 Consult Now
Hi, How Can We Help You?

Category Archives: RBI on FEMA , LRS and ODI

October 12, 2026

India Inc. Abroad: RBI’s August 2026 Outward Investment Data

Oct 22, 2026 · @Prashant Ajmera

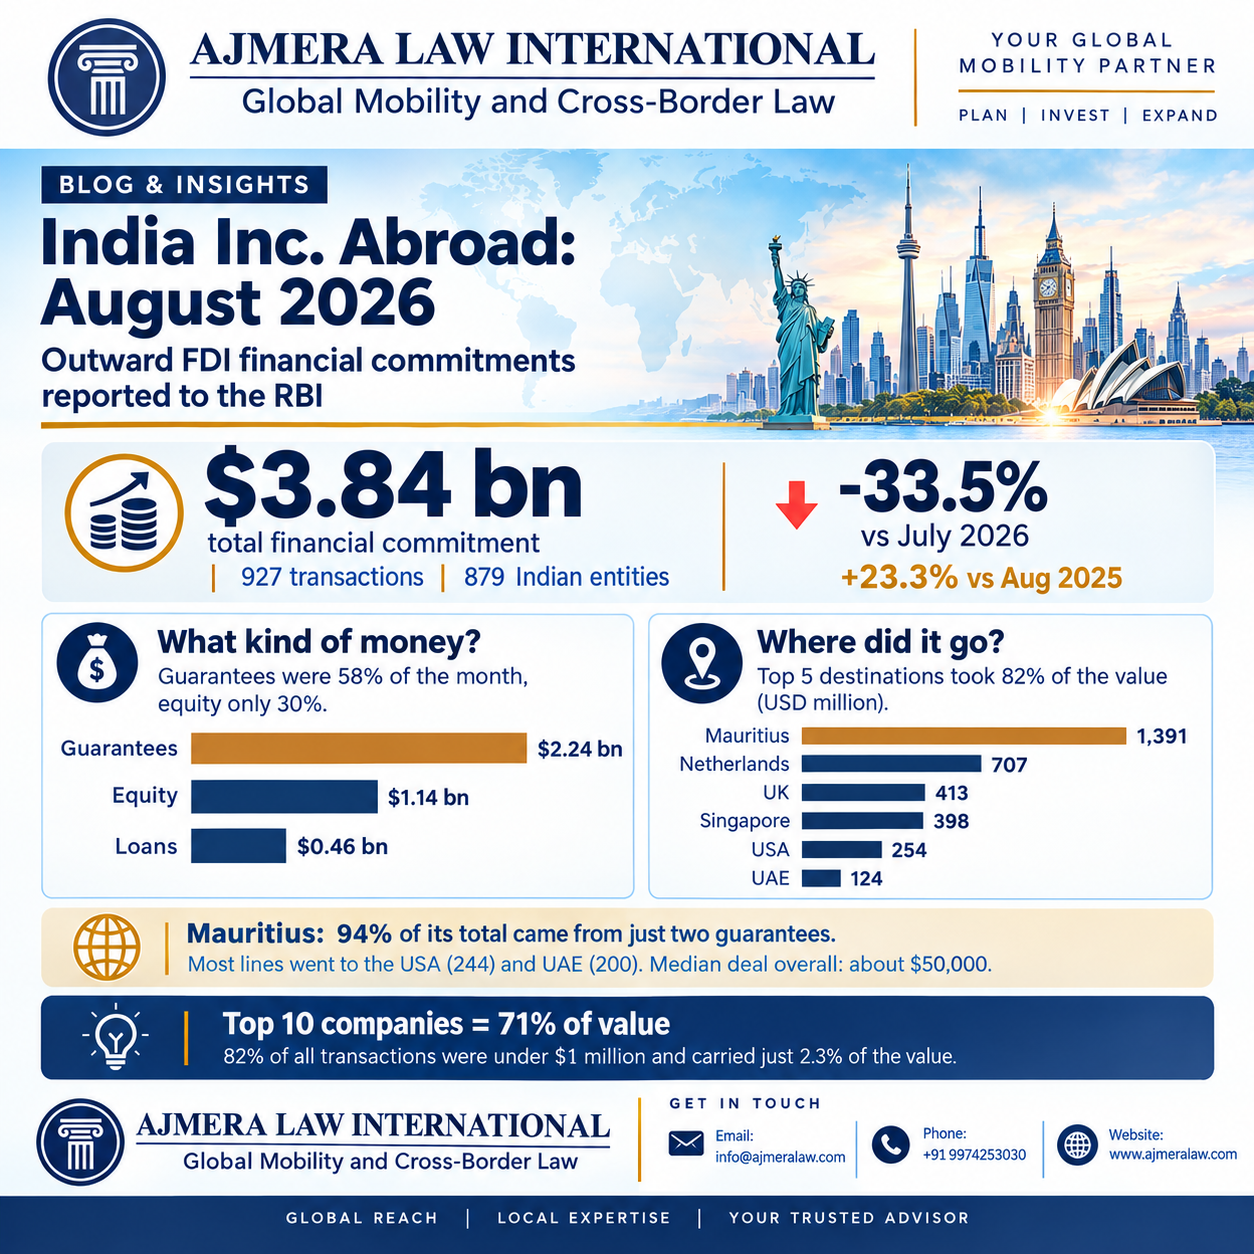
Indian businesses committed USD 3.84 billion to overseas joint ventures and subsidiaries in August 2026, 33.5% less than July but 23.3% more than August 2025, and guarantees, not cash, made up most of it.

Guarantees, not cash, drove the month

Guarantees were 58.2% of August’s USD 3.84 billion, against 29.7% for equity and 12.1% for loans. A guarantee is a promise to back a foreign subsidiary’s obligations, so it counts as a commitment but is not cash leaving India that month.

Component Aug 2026 (USD mn) Share vs Jul 2026 vs Aug 2025
Equity 1,140.5 29.7% -44.5% +7.3%
Loan 464.2 12.1% -47.2% -45.1%
Guarantee 2,235.3 58.2% -21.3% +85.3%
Total 3,840.0 100% -33.5% +23.3%

Only 39 of the 927 transactions involved a guarantee. Four of them made up 81.6% of all guarantee value: Solar Industries India (USD 795.0 million), Jindal Power (USD 514.8 million), Tata Communications (USD 288.8 million) and Owens Corning (India) (USD 225.0 million).

What does “guarantee issued” mean?

A guarantee issued is a promise by an Indian company to back the obligations of its overseas joint venture or subsidiary, usually a loan from a foreign lender. If the overseas entity cannot pay, the Indian parent must step in. No cash leaves India when the guarantee is issued, so it is a contingent commitment, not a transfer of money. The RBI still counts it as part of the overseas financial commitment, alongside equity and loans, which is why it uses up the same investment limit.

Where the money went

Five destinations took 82.4% of the value, yet the USA and UAE had far more transactions than any of them.

Destination Total (USD mn) Share Transactions of which equity (USD mn)
Mauritius 1,391.1 36.2% 10 6.7
Netherlands 706.6 18.4% 10 257.2
United Kingdom 412.7 10.7% 51 98.4
Singapore 398.4 10.4% 93 326.7
USA 254.1 6.6% 244 177.2
UAE 124.0 3.2% 200 77.7
Australia 101.0 2.6% 15 2.3
Saudi Arabia 93.7 2.4% 22 0.8
British Virgin Islands 68.8 1.8% 4 1.0
IFSC GIFT City 48.5 1.3% 39 9.3

Mauritius is first only because of two guarantees, Solar Industries India and Jindal Power, which make up 94% of its USD 1,391.1 million. For actual equity, Singapore led (USD 326.7 million across 93 transactions), followed by the Netherlands (USD 257.2 million) and the USA (USD 177.2 million). The USA (244) and the UAE (200) recorded the most transactions, and GIFT City drew 39 worth USD 48.5 million. In all, 79 destinations appear in the data. Each is the first overseas entity, not necessarily the final market, because holding structures sit in between.

Sectors and deal sizes

Manufacturing led with 28.3% of the value, while financial and business services had the most transactions (399). The sector is RBI’s label for the overseas entity’s main activity, not the Indian company’s own industry.

Sector of overseas entity Total (USD mn) Share Transactions Equity (USD mn) Guarantees (USD mn)
Manufacturing 1,086.9 28.3% 152 238.9 814.7
Financial, insurance and business services 722.7 18.8% 399 334.4 303.3
Agriculture and mining 576.1 15.0% 28 373.0 158.4
Electricity, gas and water 524.7 13.7% 10 1.1 516.2
Transport, storage and communication 504.7 13.1% 42 63.6 317.1
Construction 216.5 5.6% 40 27.9 86.1
Wholesale, retail, restaurants and hotels 168.6 4.4% 210 87.8 16.9
Miscellaneous 22.5 0.6% 2 1.0 21.5
Community, social and personal services 17.2 0.4% 44 12.9 1.0

Outbound India runs at two speeds. The ten largest Indian companies account for 70.8% of the month (USD 2,719.0 million), and six transactions of USD 100 million or more made up 61.9% of the value. At the other end, 759 of 927 transactions (81.9%) were under USD 1 million and together carried only 2.3% of the value. The median transaction was USD 50,000, and 726 transactions were equity-only.

Wholly owned subsidiaries accounted for 638 transactions and USD 3,402.4 million (88.6%). Joint ventures accounted for 289 transactions and USD 437.6 million (11.4%).

The ten biggest commitments

The ten largest Indian companies accounted for USD 2,719.0 million, or 70.8% of August’s total, and six of them included a guarantee.

# Indian company Overseas entity Country Commitment Total (USD mn)
1 Solar Industries India Ltd Solar Overseas Mauritius Ltd Mauritius Guarantee 795.0 795.0
2 Jindal Power Ltd Jindal Power (Mauritius) Ltd Mauritius Guarantee 514.8, loan 7.4 522.2
3 Bharat PetroResources Ltd BPRL International BV Netherlands Equity 250.0, guarantee 154.5 404.5
4 Tata Communications Ltd Tata Communications Netherlands BV Netherlands Guarantee 288.8 288.8
5 Owens Corning (India) Pvt Ltd Project Spindle IHC UK2 Ltd United Kingdom Guarantee 225.0 225.0
6 Tata Steel Ltd T Steel Holdings Pte Ltd Singapore Equity 140.0 140.0
7 Adani Ports and SEZ Ltd NQXT Port Pty Ltd Australia Loan 98.2 98.2
8 Nazara Technologies Ltd Nazara Technologies UK Ltd United Kingdom Equity 33.9, loan 57.4 91.2
9 KEC International Ltd Al Sharif Group and KEC Ltd Company (JV) Saudi Arabia Guarantee 81.7 81.7
10 Sindhu Trade Links Ltd Advent Coal Resources Pte Ltd (JV) Singapore Equity 72.4 72.4

Names and amounts are as reported by authorised dealer banks to the RBI. They are commitments, not confirmation that funds have moved, and listing a company here implies nothing beyond what the RBI data shows.

What it means for businesses going abroad

A guarantee for a foreign subsidiary counts as an overseas financial commitment, just as equity and loans do, so it needs the same planning. Four practical points follow from August’s data:

  • Count guarantees in the limit. Under the FEMA (Overseas Investment) Rules, 2022, an Indian entity’s financial commitment under the automatic route is generally capped at 400% of its net worth, and guarantees form part of that commitment.
  • Report every transaction. Each investment is reported through the authorised dealer bank, and reporting obligations continue after the first remittance, including for small deals.
  • Plan the holding structure early. Mauritius, the Netherlands, Singapore and now GIFT City (39 transactions this month) each carry different tax, treaty and compliance consequences that are far cheaper to settle before investing than after.
  • Small deals are covered too. With a median transaction of USD 50,000, many outbound investors are SMEs and start-ups, and the same rules apply to them as to the large groups.

This is general information, not legal advice. Check the current rules and your own facts before acting.

==================================================================================================

The author of this article is Mr. Prashant Ajmera, an Indian immigration lawyer and Canadian citizen. He is the founder of Ajmera Law International and the author of two books, “Millionaires On The Book” and “How to Plan for Your Child’s Foreign Education.” Over the past 30 years, he has assisted and advised over 30,000 students and families on planning their foreign education and settlement. He regularly speaks at various forums on this subject.

Ajmera Law International: Mo: +91 9974253030 | info@ajmeralaw.com | www.ajmeralaw.com
 

September 28, 2026

Three Ways to Expand Your Business to the USA

A Guide to Business Immigration Options

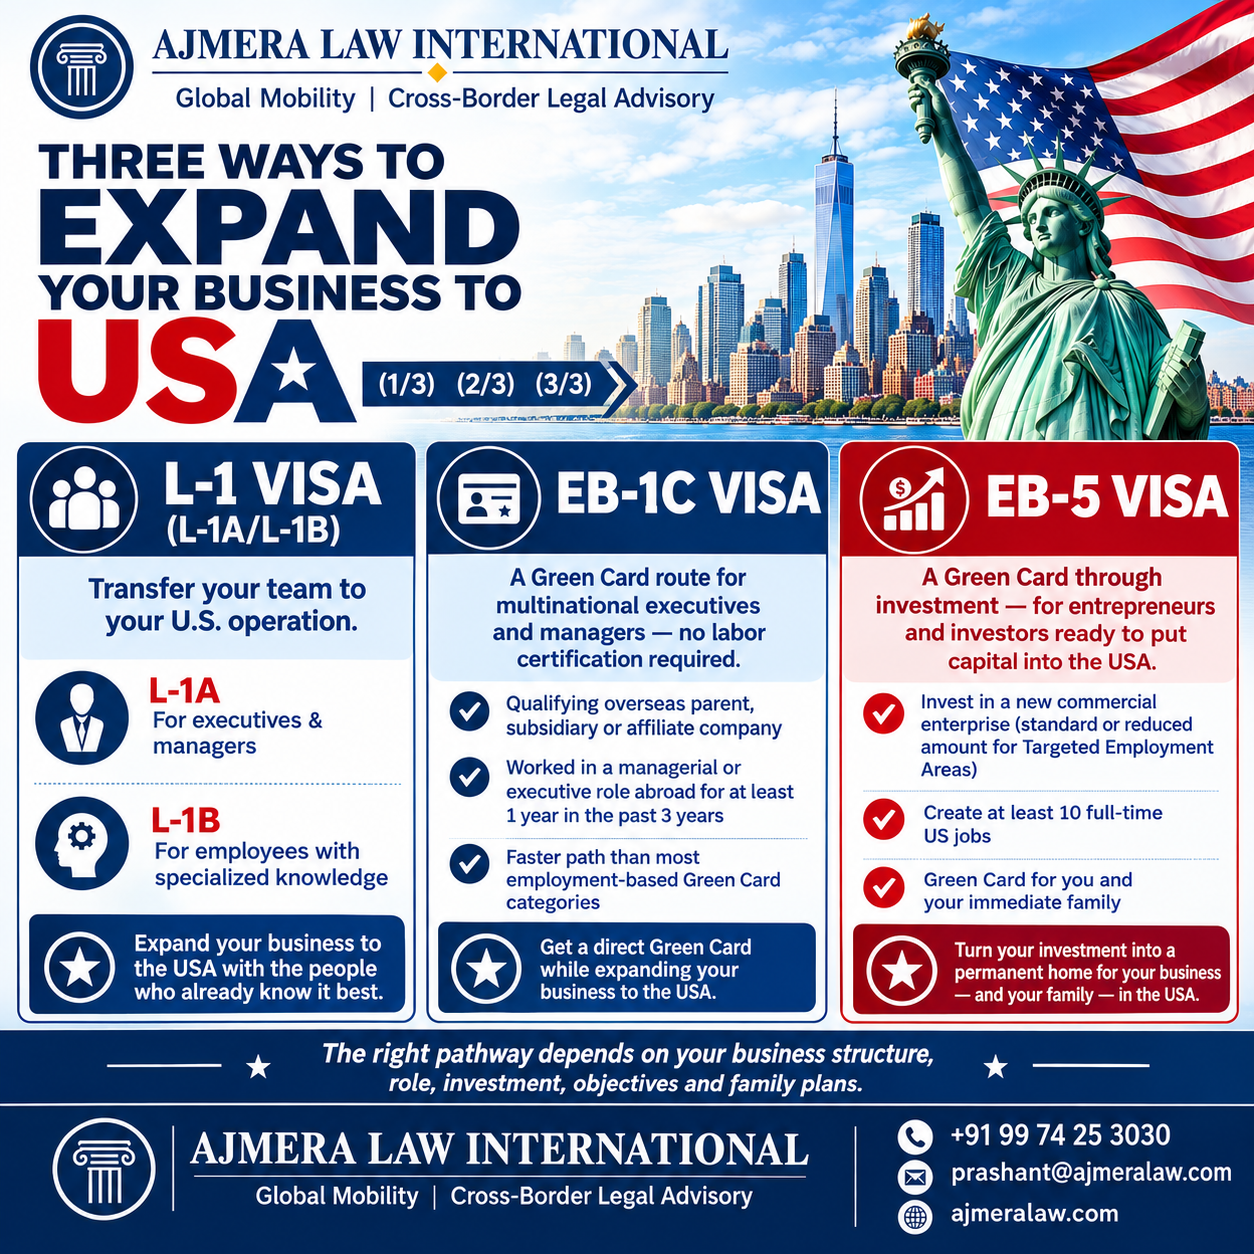
For Indian entrepreneurs and business owners, entering the American market is often less about starting from scratch and more about choosing the right legal pathway to move people, leadership, or capital across borders. U.S. immigration law offers several routes for this, but three stand out as the most commonly used by companies looking to establish, grow, or invest in a U.S. presence: the L-1 visa, the EB-1C visa, and the EB-5 visa. Each serves a different purpose, comes with its own eligibility criteria, and leads to different long-term outcomes. Understanding how they differ, and how they can work together, is essential for any business owner planning a serious move into the U.S. market.


1. Expanding Through People: The L-1 Visa

The L-1 visa is designed for companies that already have an established business outside the United States and want to open, run, or grow a U.S. office by transferring their own staff, rather than hiring locally from day one. It is a non-immigrant visa, meaning it is temporary in nature, but it is one of the most flexible and widely used tools for cross-border business expansion because it does not require a labor certification or proof that no qualified American worker is available for the role. The employer simply needs to demonstrate a genuine business need and a qualifying relationship between the overseas company and the U.S. entity.

There are two categories under the L-1 visa. The L-1A is for executives and managers, and covers individuals who will direct the organization, a major function within it, or a team of professional employees. This is typically the category used by business owners themselves, or by senior leadership being sent to establish and run the U.S. operation.

The L-1B is for employees with specialized knowledge, meaning individuals who possess an advanced level of expertise in the company’s products, services, research, systems, or processes that is not commonly found in the broader labor market. This category is often used for technical staff, engineers, or subject-matter experts whose knowledge is critical to setting up or operating the U.S. business.

To qualify for either category, the employee must have worked for the overseas company for at least one continuous year within the three years immediately preceding the application. The overseas and U.S. entities must also have a qualifying relationship, such as parent and subsidiary, affiliate, or branch office, and both entities must be actively doing business, not simply holding an office on paper.

One of the most valuable features of the L-1 visa is the new office provision, which allows a company that does not yet have a functioning U.S. office to still bring over an executive or manager to establish one. In this case, the initial approval is limited to one year, after which the company must show that the U.S. office is operating, generating revenue, and has hired staff, in order to extend the visa further. This makes the L-1 an ideal entry point for businesses that are serious about a U.S. presence but are still in the early stages of building it.

Once approved, the L-1A visa can be extended up to a maximum of seven years, while the L-1B can be extended up to five years. Spouses of L-1 visa holders receive L-2 status, which allows them to apply for work authorization in the U.S., and children can attend school on the same dependent status. Perhaps most importantly for long-term planning, L-1A status creates a natural and efficient bridge to permanent residency, because L-1A executives and managers are the exact profile targeted by the next category: the EB-1C visa.

2. From Transfer to Green Card: The EB-1C Visa

While the L-1 visa is temporary, the EB-1C is an immigrant visa category, meaning it leads directly to a Green Card from India. It is specifically designed for multinational executives and managers who have been working abroad for a company that has a qualifying U.S. affiliate, and who now wish to continue in an executive or managerial capacity for the U.S. entity on a permanent basis.

The eligibility requirements mirror those of the L-1A in many respects. The applicant must have worked in a managerial or executive role abroad for at least one year within the three years before filing, and there must be a qualifying relationship between the U.S. company and the overseas entity. The U.S. company must also have been doing business for at least one year at the time of filing. Because of this overlap, the EB-1C is often pursued as the natural next step after an individual has spent time in the U.S. on an L-1A visa, having already demonstrated that the U.S. office is functioning and that the executive role is genuine.

What makes the EB-1C particularly attractive compared to most other employment-based Green Card categories is that it does not require labor certification. Most employment-based immigrant visas require the employer to first test the U.S. labor market and obtain a certification from the Department of Labor showing that no qualified American worker is available for the position. This process, known as PERM, can take well over a year on its own. The EB-1C skips this step entirely, which significantly shortens the overall timeline and reduces administrative burden, making it one of the more efficient employment-based Green Card routes available.

That said, processing times for EB-1C petitions are still subject to the U.S. visa bulletin, which allocates a limited number of Green Cards each year by country of birth. Applicants born in countries with high demand, notably India, may experience longer waiting periods for their priority date to become current, even after the petition itself is approved. This is an important planning consideration, and one where early filing can make a meaningful difference over time.

The outcome of a successful EB-1C petition is significant: a direct, permanent Green Card for the applicant, along with the applicant’s spouse and unmarried children under 21. There is no need to first hold a temporary L-1 visa to qualify for EB-1C, though in practice, many successful applicants do use the L-1A as a stepping stone, since it allows the U.S. business to establish a track record before the permanent petition is filed.

3. Building a Presence Through Capital: The EB-5 Visa

The third major route, and the one most distinct from the other two, is the EB-5 visa. Rather than being based on an employment relationship or a transfer of personnel, the EB-5 is an investment-based Green Card category. It is designed for individuals who are willing to invest a significant amount of capital into a new commercial enterprise in the United States and, in doing so, create jobs for American workers.

The minimum investment threshold depends on the location of the project. For investments made in a Targeted Employment Area, meaning a rural area or a region with high unemployment, the required investment is 800,000 US dollars. For projects outside a Targeted Employment Area, the standard investment amount is 1,050,000 US dollars. In either case, the investment must be at risk, meaning it must be placed into a genuine commercial enterprise with the potential for gain or loss, rather than simply parked in a safe or guaranteed instrument.

The central requirement of the EB-5 program is job creation. The investment must directly or indirectly create or preserve at least ten full-time jobs for qualifying U.S. workers within a defined period. There are two broad ways to meet this requirement. The first is direct investment, where the investor starts or invests in their own business and is directly responsible for creating the required jobs. The second, and by far the more common route among Indian investors, is investment through a Regional Center, which is a USCIS-designated entity that manages larger development projects and pools capital from multiple investors. Regional Center investments allow for a more passive role, since job creation can be counted using indirect and induced employment models, and the investor is not required to be involved in the day-to-day management of the business.

Because EB-5 does not require the investor to work for or manage the enterprise personally, it is often the preferred route for business owners, professionals, or families who want a Green Card primarily for lifestyle, education, or long-term security reasons, rather than to actively operate a U.S. business themselves. It is worth noting, however, that EB-5 approval is initially conditional. Investors and their families receive a two-year conditional Green Card, and must later file a petition to remove the conditions by demonstrating that the required jobs were, in fact, created and that the investment remained at risk throughout the required period.

Like the EB-1C, EB-5 approval extends to the investor’s spouse and unmarried children under 21, making it a strong option for families planning a long-term move. Unlike the L-1 and EB-1C categories, EB-5 does not require any employer sponsorship at all. The investor is entirely self-sponsored, which removes the dependency on an existing overseas business or employment relationship, and opens the door to individuals who may not have a company to transfer staff from, but do have the capital to invest.

Choosing the Right Path

Each of these three categories serves a different kind of business goal. The L-1 visa is best suited to companies that already have an operating business abroad and want to move their own people to establish or grow a U.S. presence, with a realistic path to later convert that presence into a permanent Green Card through EB-1C. The EB-1C is the natural long-term destination for executives and managers who have proven, often through the L-1, that their U.S. operation is genuine and functioning. The EB-5, by contrast, does not depend on an existing business or employment history at all, and instead offers a direct route to permanent residency through capital investment and job creation, making it especially attractive to investors and families seeking a more passive path to a U.S. Green Card.

For many businesses, these routes are not mutually exclusive but sequential. A company might begin with an L-1 visa to establish its U.S. office, and once that office is operating successfully, its executive can pursue an EB-1C Green Card. Alternatively, a business owner without an existing company structure suited to L-1 or EB-1C may find that EB-5 offers the most direct path to permanent U.S. residency for the entire family.

Given the complexity of eligibility requirements, documentation, and processing timelines involved in each of these categories, working with experienced legal counsel from the outset is essential to choosing the right strategy and avoiding costly delays.

4. Bonus Path

There is also a fourth possibility, distinct from all three immigration routes above, for Indian HNIs and UHNIs who want to invest in the United States purely for financial reasons, with no visa or residency expectation attached. This route is suited to investors seeking higher returns, geographic diversification of their portfolio, and a way to build a corpus for their children’s future education abroad. The investment could be in land, real estate or financial market.


Ajmera Law International advises businesses and individuals on global mobility and U.S. business immigration strategy, including L-1, EB-1C, and EB-5 matters.

Contact: Advocate Prashant Ajmera

+91 9974253030  |  prashant@ajmeralaw.com  |  ajmeralaw.com

September 22, 2025

Offshore Bank Accounts: Guidelines and Compliance

Effective management of banking and financial transactions is critical for Indian businesses expanding internationally. This module explores the guidelines and practical strategies for opening and operating offshore bank accounts while mitigating financial risks such as currency fluctuations through derivatives and advanced tools.

Regulatory Framework
Under the Foreign Exchange Management Act (FEMA) and Reserve Bank of India (RBI) circulars, Indian entities can establish and operate foreign currency accounts overseas under specified conditions.

Eligibility

  • Indian companies with branches, subsidiaries, or joint ventures abroad 
  • Exporters with active foreign currency inflows 

Approval Process

  • Automatic Route: RBI permits certain offshore accounts without prior approval, for uses like remittance of profits or covering operating expenses. 
  • Approval Route: Special permission is needed for large transactions or unique financial arrangements. 

Permitted Transactions

  • Crediting export receipts 
  • Settling overseas operational expenses 
  • Remitting dividends, royalties, or capital gains 

Documentation

  • Application through an Authorized Dealer (AD) Bank in India 
  • Company resolution, identity verification, business rationale for offshore accounts 
  • Adherence to KYC requirements of the foreign bank 

Currency Risk Management: Hedging Against Volatility

Understanding the Risk
Foreign trade exposes businesses to exchange rate risks, common in export-import, overseas loans, and cross-border investments.

Hedging Tools

  • Forward Contracts: Lock in exchange rates for future transactions 
  • Currency Futures: Exchange-traded contracts to protect against price shifts 
  • Options Contracts: Right (not obligation) to exchange at a specified rate 
  • Swaps: Exchange of cash flows or principal in different currencies 

RBI Guidelines

  • Permits use of derivatives exclusively for hedging, not speculation 
  • Transactions routed through RBI-authorized dealers 
  • Clear documentation, such as invoices or contracts, must justify every hedging transaction 

Practical Considerations for Offshore Banking

Choosing the Right Bank
Evaluate:

  • Local legal and regulatory environment 
  • Transaction fees and foreign exchange charges 
  • Digital banking facilities for cross-border ease 
  • Anti-money laundering (AML) compliance 

Currency Denomination

  • Maintain accounts in major currencies relevant to your trade 
  • Diversify holdings across multiple currencies to balance exposure 

Repatriation of Profits

  • Profits remitted back to India must comply with FEMA 
  • Tax planning is essential to minimize double taxation and withholding tax levies 

Tax Implications and Reporting

Tax Treatment

  • Offshore income must comply with Indian Income Tax Act provisions 
  • Relief can be availed under Double Taxation Avoidance Agreements (DTAA) 

Reporting Obligations

  • Companies must disclose offshore accounts in their annual financial statements 
  • Individual stakeholders must declare foreign assets in their income tax returns, where applicable 

Examples and Case Studies

  • Infosys: Leveraged offshore banking facilities to streamline payroll and supplier payments across international markets. 
  • Tata Steel: Used forward contracts to hedge against USD-INR volatility, protecting margins in global trade. 

Conclusion

This module enables Indian businesses to seamlessly manage international financial operations. By setting up offshore bank accounts in compliance with FEMA, using RBI-approved hedging tools, and adhering to tax reporting obligations, companies can reduce global financial risks. With the right mix of compliance, planning, and risk management, Indian enterprises can safeguard profitability and sustain long-term growth in global markets.

September 1, 2025

Online Filing Systems: Overview of RBI’s Foreign Investment Reporting and Management System (FIRMS) – #9

With globalization driving Indian businesses to expand abroad, one of the most crucial enablers of smooth international operations is regulatory compliance. The Reserve Bank of India (RBI) has introduced the Foreign Investment Reporting and Management System (FIRMS) to streamline and digitize the reporting of cross-border investments under the Foreign Exchange Management Act (FEMA).

This module provides an in-depth overview of FIRMS, its key components, and its importance for Indian businesses seeking seamless global expansion.

1. Introduction to FIRMS

What is FIRMS?
FIRMS is an integrated online portal by the RBI, designed to simplify the process of reporting foreign investment transactions. It is used by Indian companies, startups, and individuals involved in Foreign Direct Investment (FDI) or Overseas Direct Investment (ODI).

Purpose of FIRMS:

  • Ensure compliance with FEMA and RBI regulations.
  • Provide a centralized system for reporting inflows and outflows of foreign investments.

Why Businesses Need FIRMS:

  • Mandatory for Indian companies setting up subsidiaries, branch offices, or joint ventures abroad.
  • Standardizes investment reporting and reduces regulatory risks.
  • Promotes transparency in cross-border financial dealings.

2. Key Modules within FIRMS

  • Single Master Form (SMF):
    Consolidates reporting of multiple transactions, including FDI, ODI, and External Commercial Borrowings (ECBs).
  • Entity User Registration:
    Businesses must register on the FIRMS portal before filing investment-related forms.
  • Foreign Currency Transfer (FC-TRS):
    For reporting the transfer of shares or convertible securities between residents and non-residents.
  • Forms for Overseas Expansion:
    • Form ODI (Overseas Direct Investment): Reporting investments in branches, subsidiaries, or JVs abroad.
    • Form APR (Annual Performance Report): Annual filing on the operational and financial performance of overseas entities.
    • Form FLA (Foreign Liabilities and Assets): Annual return to report foreign assets and liabilities for RBI records.

3. FIRMS Registration and Filing Process

a) Entity Registration

  1. Log in to the FIRMS portal and create an entity account.
  2. Submit required KYC documents, such as Certificate of Incorporation, PAN, and signatory details.
  3. Obtain login credentials for forms like ODI and FLA.

b) Filing Form ODI

  • Include details like nature of investment (branch, subsidiary, JV), source of funds, jurisdiction of the foreign entity, and investment amount.
  • Must be filed before making any financial commitment abroad.

c) Post-Investment Compliance

  • Submit APR annually to update financial results of overseas operations.
  • File changes or updates in structure through the ODI form.
  • Ensure FLA filing for RBI’s statistical database.

4. Practical Aspects for Indian Businesses

Benefits of FIRMS:

  • Real-time tracking of investment reports.
  • Eliminates duplication and manual paperwork.
  • Faster approvals and integrated FEMA compliance.

Challenges and Solutions:

  • Challenge: Complex filing and occasional portal-related issues.
  • Solution: Work with compliance professionals (lawyers, CAs) and prepare documentation in advance.

Importance of Timely Filing:

  • Delays or non-compliance can attract heavy FEMA penalties.
  • Stay updated with RBI circulars to avoid lapses.

5. Country-Specific Considerations

  • United States (US): ODI reporting supports compliance with tax treaty obligations.
  • United Kingdom (UK): FIRMS filings must be completed alongside Companies House obligations.
  • United Arab Emirates (UAE): Ensures FEMA compliance for businesses setting up UAE branches or subsidiaries.

Conclusion

The FIRMS portal is a cornerstone of regulatory compliance for Indian businesses investing abroad. By consolidating multiple reporting requirements into a single platform, it enhances transparency and efficiency while reducing the risk of penalties.

For businesses with global ambitions, understanding and using FIRMS effectively ensures smooth overseas expansion, strengthens compliance frameworks, and contributes to long-term international growth.

July 7, 2025

Beyond Borders: Establishing Indian Businesses Abroad – #1

Expanding a business globally is more than just ambition—it requires a strategic approach backed by thorough research. For Indian entrepreneurs, entering international markets involves navigating diverse cultures, legal frameworks, consumer behaviors, and economic conditions.

This journey begins with research, the cornerstone of global expansion. It helps businesses understand market demands, identify competitors, and evaluate risks and opportunities. By investing in research, Indian entrepreneurs equip themselves with the tools to adapt, innovate, and thrive in the global arena.

Why Research is Critical for Global Expansion

Research enables informed decision-making, minimizes costly errors, and ensures compliance with local regulations. In a world driven by knowledge, it is an essential investment for success. Whether exporting, establishing a branch office, or setting up a wholly-owned subsidiary, Indian businesses can benefit from a wide array of tools, websites, and government portals tailored to their needs.

Government Portals for Market Insights

  1. Ministry of Commerce and Industry: https://www.commerce.gov.in
  2. Export Promotion Council of India (EPCH): https://www.commerce.gov.in/useful-links/export-promotion-councils/
    • Facilitates and promotes exports of Indian products.
    • Provides market insights, trade fairs, and buyer-seller meets.
  3. Directorate General of Foreign Trade (DGFT): https://www.dgft.gov.in
    • Offers trade statistics, export-import policies, and regulations.
    • Access to FTP schemes like MEIS and SEIS for export incentives.
  4. India Trade Portal: https://www.indiantradeportal.in
    • Comprehensive database of market access information, tariffs, and trade barriers.
  5. Make in India: https://www.makeinindia.com
    • Provides insights into investment opportunities and export promotion policies.
  6. Invest India: https://www.investindia.gov.in
    • Offers consultancy for businesses seeking international expansion.
    • Provides information on FDI policies, overseas opportunities, and global trade shows.
  7. FIEO (Federation of Indian Export Organizations): https://www.fieo.org
    • Guidance on export documentation and procedures.
    • Access to global tenders and business opportunities.
  8. RBI Foreign Investment Reporting: https://fir.rbi.org.in
    • Mandatory portal for overseas direct investment (ODI) compliance.
  9. Startup India: https://www.startupindia.gov.in
    • Resources and support for startups looking to expand globally.

Market Research Tools and Websites

  1. Trade Map: https://www.trademap.org
    • Analyzes international trade flows and identifies export opportunities.
    • Country-specific data on imports, exports, and tariffs.
  2. World Bank Doing Business Report: https://www.doingbusiness.org
    • Provides ease-of-doing-business rankings and insights into regulations in different countries.
  3. ITC Market Access Map: https://www.macmap.org
    • Offers tariff rates, trade agreements, and non-tariff measures by country.
  4. WTO Tariff Database: https://www.wto.org
    • Access global tariff schedules and trade agreements affecting Indian exports.
  5. Exim Bank of India: https://www.eximbankindia.in
    • Provides financing options, research, and market reports for Indian exporters.
  6. Euromonitor International: https://www.euromonitor.com
    • Offers in-depth industry and market research reports.
  7. Statista: https://www.statista.com
    • Global statistics on industries, markets, and consumer behaviors.

Trade Associations and Chambers of Commerce

  1. Confederation of Indian Industry (CII): https://www.cii.in
    • Organizes trade delegations and events to connect Indian businesses with global markets.
  2. Indo-Global Chambers of Commerce: https://www.indoglobalchamber.org
    • Provides networking opportunities and market insights for Indian businesses expanding abroad.
  3. GlobalLinker: https://www.globallinker.com
    • A platform for SMEs to connect with international business partners.

Global Directories and Databases

  1. Alibaba: https://www.alibaba.com
    • Useful for sourcing materials and identifying potential buyers in foreign markets.
  2. LinkedIn Sales Navigator: https://www.linkedin.com/sales
    • Helps in identifying decision-makers and potential business partners in target markets.
  3. Global Trade Directory: https://www.globaltradedirectory.com
    • A directory of service providers in foreign markets for exporters and businesses.

Logistics and Supply Chain Tools

  1. ICEGATE (Indian Customs Electronic Gateway): https://www.icegate.gov.in
    • Information on customs regulations, tariffs, and export-import documentation.
  2. UNCTAD e-Regulations: https://eregulations.org
    • Details on procedures for trade and investment in various countries.
  3. Freightos: https://www.freightos.com
    • A platform to compare shipping rates and streamline logistics.

Cultural and Regulatory Insights

  1. Hofstede Insights: https://www.hofstede-insights.com
    • Understand cultural dimensions for building international relationships.
  2. Global Edge: https://globaledge.msu.edu
    • Offers guides on market entry, regulations, and business practices in different countries.

Practical Steps Using These Tools

  1. Start with India Trade Portal and Trade Map for market research.
  2. Analyze tariff structures using ITC Market Access Map and WTO Tariff Database.
  3. Check ease-of-doing-business rankings through the World Bank Doing Business Report.
  4. Identify potential partners using LinkedIn Sales Navigator or Alibaba.
  5. Understand local regulations with the help of UNCTAD e-Regulations and Invest India.

These resources collectively provide a robust foundation for Indian businesses to research foreign markets and navigate the complexities of global expansion effectively. By leveraging these tools and strategies, you can take your business beyond borders and into the global arena.

June 1, 2023

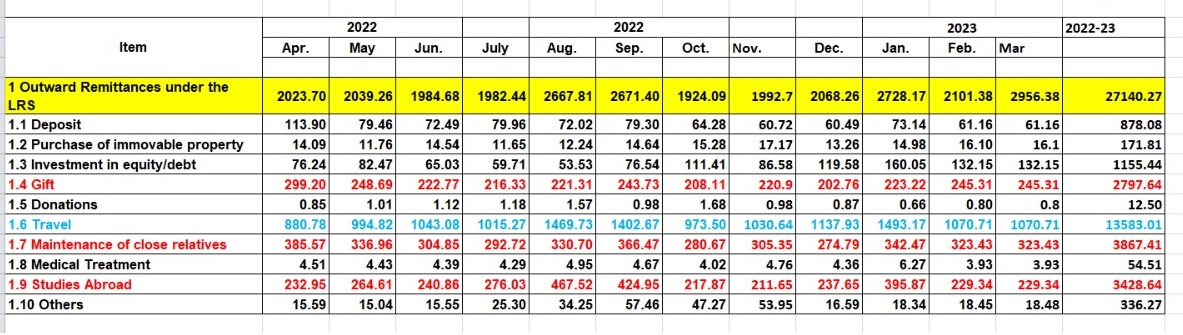
Recent data from the Reserve Bank of India (RBI) shows that Indian high-net-worth individuals (HNIs) remitted a total of US$27 billion out of India in the financial year 2022-23. This is a significant increase from the previous year’s figure of US$19.5 billion.

The RBI data shows that the majority of this remittance was used for foreign travel (US$13.5 billion), followed by education (US$10 billion) and gifts to relatives (US$3 billion). Only a small portion of the remittance (US$2 billion) was invested in foreign assets, such as equity, debt, and real estate.

This data raises the question of whether Indian HNIs are managing their wealth properly. On the one hand, the high level of remittance suggests that Indian HNIs are confident in the Indian economy and are willing to spend their money on foreign goods and services. On the other hand, the low level of investment in foreign assets suggests that Indian HNIs are not taking advantage of the opportunities available in global markets.

There are a number of possible explanations for this discrepancy. One possibility is that Indian HNIs are simply not aware of the investment opportunities available outside of India. Another possibility is that they are concerned about the risks associated with investing in foreign markets. Finally, it is also possible that they are simply not comfortable with the idea of investing their money outside of India.

Whatever the reason, the RBI data suggests that Indian HNIs have a significant opportunity to improve their wealth management. By investing in foreign assets, they can diversify their portfolios and protect their wealth from the risks associated with a single currency. They can also take advantage of the higher growth rates and lower taxes that are often available in foreign markets.

The RBI data is a wake-up call for Indian HNIs. It is time for them to start thinking about their wealth management in a more globalized way. By investing in foreign assets, they can improve their financial security and ensure that their wealth lasts for generations to come.

In addition to the reasons mentioned above, there are a few other factors that may be contributing to the low level of investment by Indian HNIs in foreign assets. These include:

·        Lack of information and resources: Indian HNIs may not have access to the same level of information and resources as their counterparts in developed countries. This can make it difficult for them to identify and evaluate investment opportunities in foreign markets.

·        Regulatory hurdles: The Indian government has put in place a number of regulatory hurdles that make it difficult for Indian HNIs to invest in foreign assets. These hurdles can add to the cost and complexity of investing and can discourage some HNIs from investing altogether.

·        Taxation: Indian HNIs are subject to a number of taxes on their foreign investments. These taxes can erode the returns on their investments and can make it less attractive to invest in foreign assets.

The RBI data highlights the need for the Indian government to take steps to make it easier for Indian HNIs to invest in foreign assets. This could include providing more information and resources to HNIs, reducing regulatory hurdles, and simplifying the tax regime. By taking these steps, the government can help Indian HNIs to improve their wealth management and protect their wealth from the risks associated with a single currency.

1